In short
Banking apps rarely lose customers in a breach. They lose them in small moments: a balance nobody can explain, a transfer stuck on "Processing", a buy-or-sell screen, a form that forgets twenty minutes of typing. This is how we design money movement, payment states, security checks, compliance prompts and AI disclosures so people always know where their money is — and why we start with an audit.
In this article
- What banking app UX actually means
- Where trust breaks first: an app that looks abandoned
- Design for the audience you actually have
- Banking is a mobile problem: kill the endless form
- The banking journeys and risk moments that matter most
- Navigation and a home screen people can read
- Balances and transactions people understand
- Money movement: show everything before the button
- SWIFT, SEPA, ACH: explain the jargon in one line
- Currency exchange: “you give” and “you receive”
- The eight states of a payment
- Bill payments and scheduled payments
- Card controls without guesswork
- Alerts and suspicious activity
- Security that people can live with
- Compliance checks without the red siren
- AI in banking apps: say where the data goes
- Errors, disputes and the way back
- Accessibility is part of trust
- How to test and measure banking app UX
- Why banking apps start with a UX audit
- Redesign or fix: the decision rule
Banking app UX is how a finance app lets people see, move and protect their money without guessing: what they have, what will happen when they press the button, what is happening now and how to get back when something goes wrong. Trust does not come from a navy palette and a padlock icon. It comes from accurate status, visible consequences, friction where the risk is real and a way back that works.
Most banking apps do not lose customers in a dramatic breach. They lose them in small, stupid moments. A balance that does not match the one the user did in their head. A transfer that says “Processing” for three days. A currency screen that asks whether you want to “buy” or “sell” when you only wanted to get home with some euros. A form that forgets twenty minutes of typing because the laptop died.
We have designed more than ten banking and fintech apps, for enterprise banks and for consumer products, and we have audited many more. The pattern barely changes. The team asks for a redesign. The problem is not on the screens they want to redesign. It sits in the flow between them, in the states nobody drew and in the words on the one button that moves the money.
Every customer who gives up on your app is a customer you paid to acquire: the ads, the onboarding bonus, the KYC check you paid a vendor for. Confusion charges interest, and in banking the bill arrives as support calls, abandoned applications and customers who keep their salary account somewhere else.
This guide is organised around money decisions and failure recovery, not a gallery of pretty screens. It covers what users need to know before, during and after every money movement, how to make security understandable, how to explain compliance checks and AI without scaring anyone, and how to test whether any of it works.
ANODA looks beyond the screen the team wants repainted. We trace the whole money journey, connect the payment states to the customer’s next action and turn those decisions into one interface system. The Xcoins quote-to-payment work shows that approach in practice: visible charges, a clear commitment and recovery when a rate or payment fails. Your customers get answers where they make the decision, and your team gets a prioritized path out of expensive support and abandoned flows.
What banking app UX actually means
Banking app UX is the full experience of managing money in an app: getting in, understanding balances and transactions, moving money, controlling cards, reacting to alerts, recovering from errors and asking for help. Interface design is a slice of it. The rest is flow, wording, timing and the states in between.
Here is the uncomfortable part. In most apps, people do not judge the product by its best screen. They judge it by its worst moment. You can have the cleanest dashboard in the category and still lose a customer on the day a payment sits in limbo with no explanation. Nobody writes a review about a lovely balance card. Plenty write one about “where is my money”.
Trust in a banking product rests on four things, and all four are design decisions:
- Accurate status. The app says what is actually happening to the money, in words a person understands, including the boring and the bad states.
- Clear consequences. Before anything moves, the user sees what they give, what the other side receives, what it costs and when it lands.
- Proportionate friction. Security steps appear where the risk is, and not as a toll booth on every screen.
- A credible way back. When something fails, the user knows whether the money is safe, what went wrong and what to do next.
Get these right and a plain-looking app earns trust. Get them wrong and no amount of polish will save it. A padlock icon on a confusing screen is a seatbelt painted on the car door: it photographs beautifully and protects nobody.

Where trust breaks first: an app that looks abandoned
Oksana Kovalchuk, ANODA’s founder, has a blunt answer to where banking trust breaks. The first place is not security. It is the look of the product.
Trust breaks in two places. The first is a completely outdated design. The application must look maintained, not like it was abandoned and development stopped five years ago. Clean design like Apple or Stripe barely changed in ten years. It is simply an eternal fashion, like Chanel.
 Oksana KovalchukFounder & CEO, ANODA
People cannot audit your encryption. They can see your screens. When the interface looks like it was last touched in 2019 — mismatched fonts, a login screen from another era, icons from three different sets — users draw the only conclusion available to them: nobody is looking after this. If nobody is looking after the buttons, who is looking after the money?
This is not a call to chase every trend. It is the opposite. The safest visual position is the timeless one: clean layouts, generous spacing, one type family, consistent components. Apple and Stripe barely changed their core look in a decade, and nobody thinks they are abandoned, because every detail is kept in order.
What makes an app look maintained is mostly discipline, not a rebrand:
- One design system, applied everywhere, including settings, statements and error screens nobody has opened since launch.
- Current platform conventions for navigation, sheets and system dialogs, so the app feels native to the phone it runs on.
- Screens that reflect today’s product: no dead promos, no features marked “coming soon” since last spring.
- Copy that sounds like one company, not like legal, marketing and support wrote alternating paragraphs.
A neglected corner costs more than it seems. The user who stumbles into an old statement screen does not think “legacy module”. They think “this bank is falling apart”, and they move their savings on payday.
Audit check
Walk through every screen a customer can reach, including settings, statements, errors and help, and note each one that uses different components, older styles or outdated copy.
Failure evidence
Two or more visual generations inside one app. Screens that look nothing like the home screen. Reviews that mention the app “looks old” or “feels unsafe”.
Correction pattern
Bring every screen into one design system, starting with the screens tied to money and security, and retire anything that advertises a feature the product no longer has.
Design for the audience you actually have
The second place trust breaks is audience fit. Many banking apps are designed for an imaginary customer: a middle-aged professional who enjoys tables and reads terms and conditions for fun. That customer exists. They are just not the only one, and often not the one your product was built for.
A banking app for children and their parents is two products that must work together. The child needs goals, pocket money and a sense of progress. The parent needs control, approvals and visibility. A banking product for Gen Z has to speak their language, or it will be deleted before the first top-up. Hand either group a polished, pasteurised enterprise portal and you get the digital equivalent of a school uniform at a festival.
A serious-looking app for an audience that is not serious about looking serious is not trust. It is an invitation to leave.
Audience fit is not only visual style. It changes almost every decision:
- Vocabulary. “Available balance” means something to an adult. “What you can spend” means something to a twelve-year-old and to most adults too.
- Defaults. A child’s card starts with online payments off and spending limits set by the parent. A freelancer’s account starts with invoices and tax pots visible.
- Control split. Who can approve, who can see, who can change limits. In family and business banking, this matters more than any colour choice.
- Motivation. Goals and progress work for savers and young users. A power user wants speed and search, not confetti.

We once worked on a product for exactly that younger audience. The lesson was simple: the brand could be bold, but the money parts had to stay as clear as in any grown-up bank. Loud where it is fun, calm where it is money.

Audit check
Write down who the app is for, in one sentence per segment, then show the home screen and one money flow to five people from each segment and ask them what they would do next.
Failure evidence
Target users describe the app as “for my parents” or “for businesses”. Key actions are named in banking jargon the audience does not use.
Correction pattern
Set tone, vocabulary, defaults and control rules per segment, and keep the money moments equally explicit for everyone.
Banking is a mobile problem: kill the endless form
Most banking happens on a phone, standing in a queue, one-handed, with a notification waiting. Oksana’s estimate from our own projects: in about nine cases out of ten, banking UX is mobile UX. A flow designed for a desktop form, squeezed onto a phone, is a restaurant menu the size of a phone book handed to someone who is already late.
The worst offender is the long form. Account opening, loan applications, business onboarding, KYC updates. Twenty-four fields on one scrolling screen, with validation errors revealed only at the bottom.

Break long tasks into a wizard: short steps, one topic per step, a clear “Step 2 of 5”, and the ability to go back without losing anything. Wizards are not just friendlier. They make errors cheaper, because a mistake is caught on the step where it happened, not at the end of a marathon.
Then comes the rule that separates careful products from careless ones: progress must survive everything. The browser tab gets refreshed. The app crashes. The laptop battery dies. Chrome decides to restart itself for no reason. Oksana does not mince words about what happens next:
A form that you spent twenty minutes filling in, and all the data is lost — this is rage. It is ragebait, not UX. It is an attempt to destabilise your user’s mental health.
Oksana KovalchukFounder & CEO, ANODA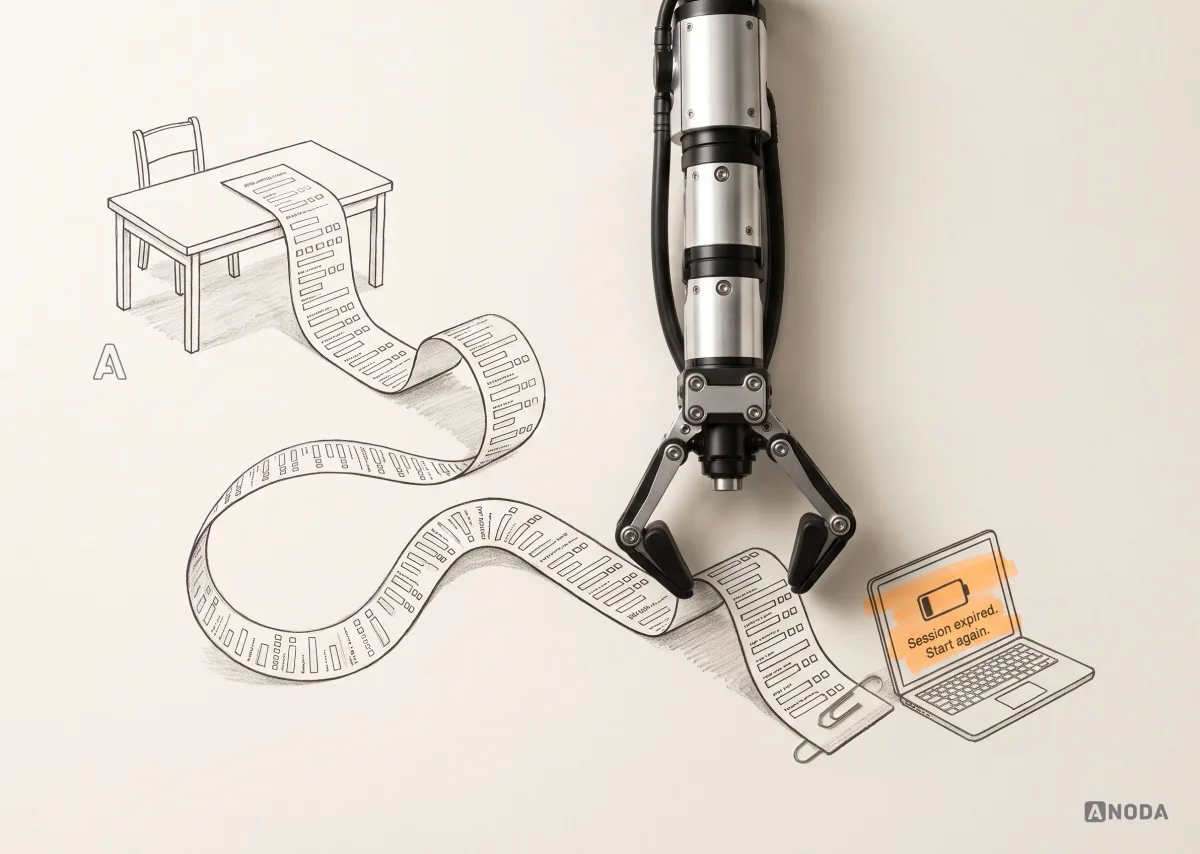
Saving progress is a design decision before it is an engineering one. Decide which data is saved after every step, how long drafts are kept, what the user sees when they come back and what happens to sensitive fields. Then design the return: a clear banner that says what was kept and where the user left off.

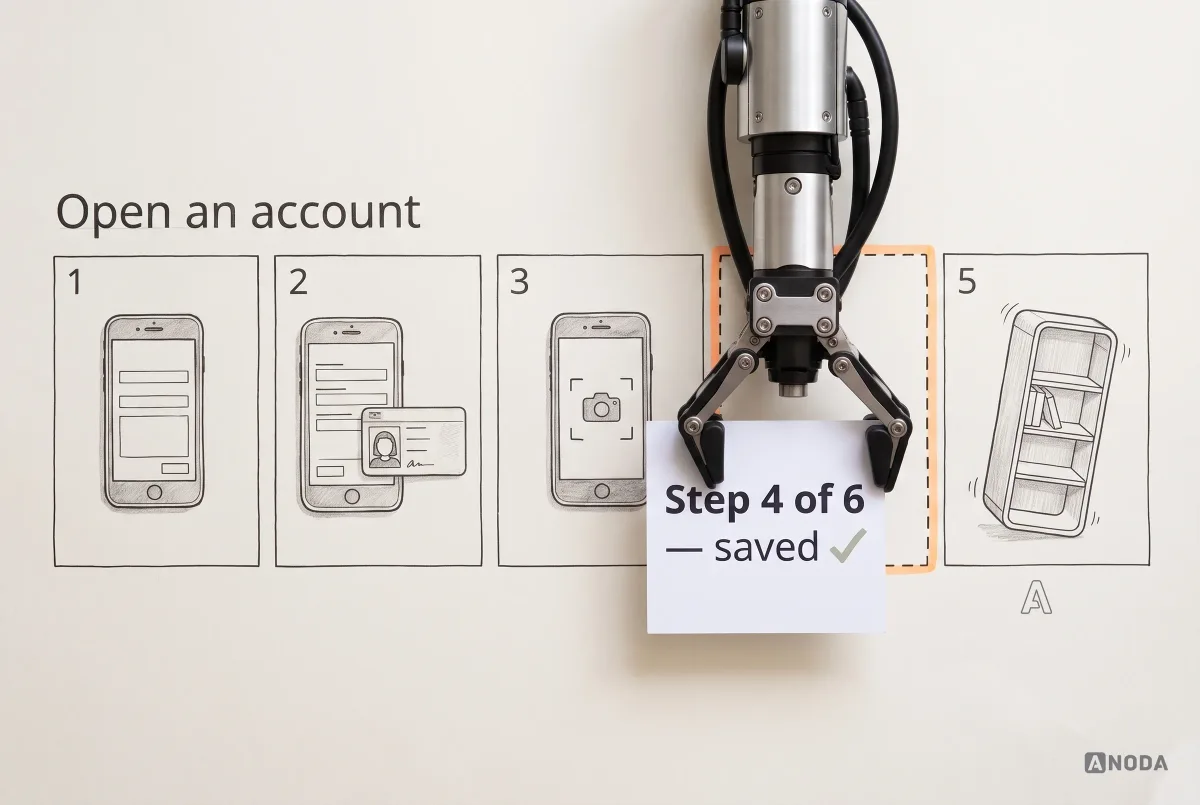
The same applies to money movements already in progress. After an interruption, first establish whether the transfer was submitted. Restore an unsubmitted draft; for a submitted or uncertain result, show the provider-confirmed status and a route to track it. Never invite a second send while the first payment may still be processing.

Audit check
Start each long flow, fill half of it, then kill the app, refresh the page, switch devices and let the session expire. Record what survives.
Failure evidence
Drafts lost on refresh or crash. Long single-page forms on mobile. Errors revealed only on submit.
Correction pattern
Split long tasks into short steps, save after every step, show a clear return path and validate each field where it is typed.
The banking journeys and risk moments that matter most
Not every screen carries the same weight. A beautifully animated spending chart is nice. A transfer screen that hides the fee is a support ticket, a chargeback and possibly a lost customer. Design effort should follow risk, and risk in banking concentrates in a handful of journeys.
| Journey | The risk moment | What the user must know |
|---|---|---|
| Sign in and recovery | Locked out, new phone, forgotten PIN | How to get back in, how long it takes, that the money is safe meanwhile |
| First-use setup | Identity checks, long forms | Why each detail is needed, how far along they are, that progress is saved |
| Balances and transactions | A number that does not match expectations | What is available, what is held and why, what each transaction is |
| Transfers and payments | Pressing “Send” | Who receives, how much, the fee, the rate, the rail and the arrival time |
| Currency exchange | Buy or sell confusion | What they give, what they receive, in which currencies, at what rate |
| Card controls | Lost card, unknown charge | The difference between freezing and cancelling, and what each changes |
| Alerts and suspicious activity | “Was this you?” | What happened, what to tap, what the bank will do |
| Disputes and support | Something went wrong | Where to report it, what happens next, when they will hear back |
| Session timeout and interruptions | Signed out mid-task | What was saved and how to continue |
Read the right-hand column again. Almost none of it is about visuals. It is about information arriving at the moment the user needs it. That is where banking app UX earns its keep or loses its customers.
Navigation and a home screen people can read
Open most banking apps and the home screen is a negotiation between departments. Marketing wants a carousel. Cards wants a banner. Loans wants a pre-approved offer. Somewhere below the fold, if you scroll, is the thing the customer opened the app for: how much money they have.

A banking home screen has one job: answer “how am I doing?” in a glance, and offer the next action. Balances first. The latest few transactions. Two or three primary actions — pay, transfer, cards. Everything else earns its place with data about usage, not with an internal stakeholder’s quarterly target.
Navigation follows the same logic. Four or five tabs, named after what people want to do, not after how the bank is organised internally. “Payments” beats “Transaction Services”. “Cards” beats “Plastic Management”. If a customer has to learn your org chart to find their card PIN, the org chart has won and the customer has lost.
Audit check
Ask ten customers to find their available balance, their last card payment and the freeze button, and time each task.
Failure evidence
The balance below the fold. Promotions above everyday actions. Tabs named after departments.
Correction pattern
Put balances and recent activity first, keep three primary actions on the home screen and name the navigation after tasks.
Balances and transactions people understand
Here is a sentence that generates thousands of support tickets: “Why is my balance lower than I thought?” The answer is usually a pending card payment, a hotel pre-authorisation, a hold on a cheque or a direct debit taken today. The bank knows the answer. The app just does not say it.
Show both numbers when they differ, and explain the gap in plain words. “Available to spend” and “Balance including pending” are different things, and the difference should be one tap away, with the pending items listed.

Transactions need the same care. The raw descriptor from the card network is written for machines. “POS 4431 SQ*COFFEEHSE LDN” is a riddle, not a transaction. Clean merchant names, a logo or category icon, the date, and a clear pending marker turn the list from an interrogation into a record the user recognises.

The detail screen is where doubts either end or escalate. Pending holds deserve an explanation: who put the hold on, whether the final amount can differ and when the hold usually drops. A customer who understands a pending hotel charge does not call you. A customer who sees 150.00 vanish and no explanation calls you, then writes about it.

Money movement: show everything before the button
This is the heart of banking app UX, and where most apps are still stingy with the truth. The rule is simple enough to write on a sticky note: before any money moves, show exactly what will happen, then ask for an explicit confirmation.
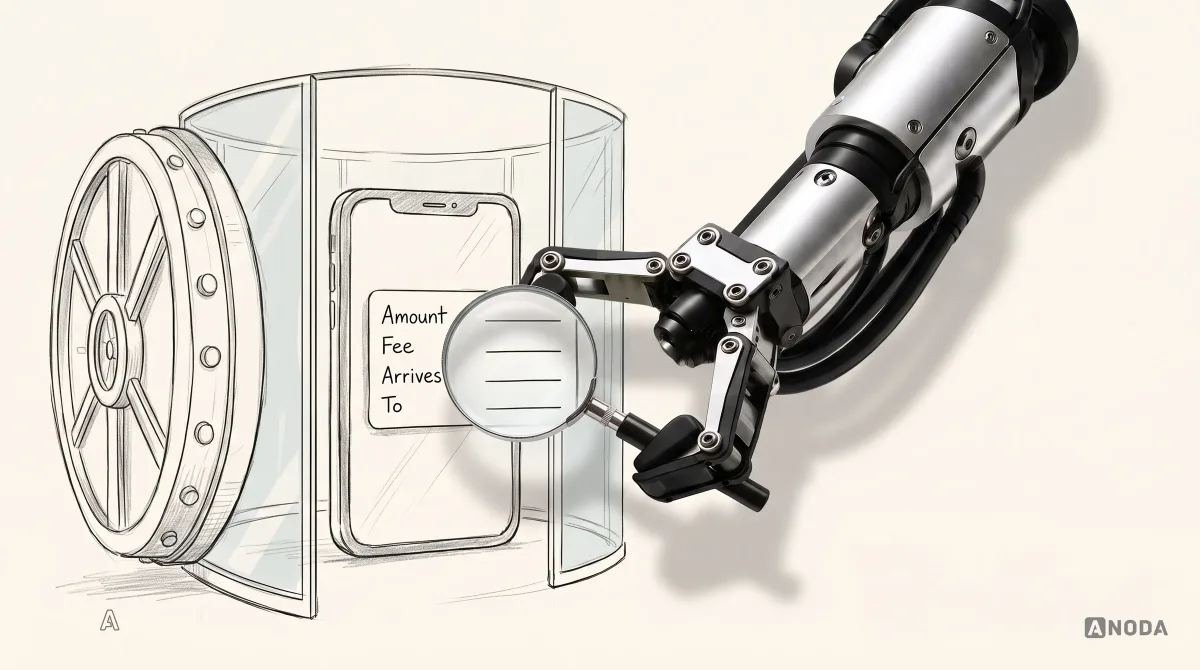
Oksana lists the minimum without hesitation: the full amount, the fee, when the transfer will complete, when the money will arrive, who will receive it, in which currency and what type of transfer it is. Anything less, and the user is signing a contract with the small print folded under the table.
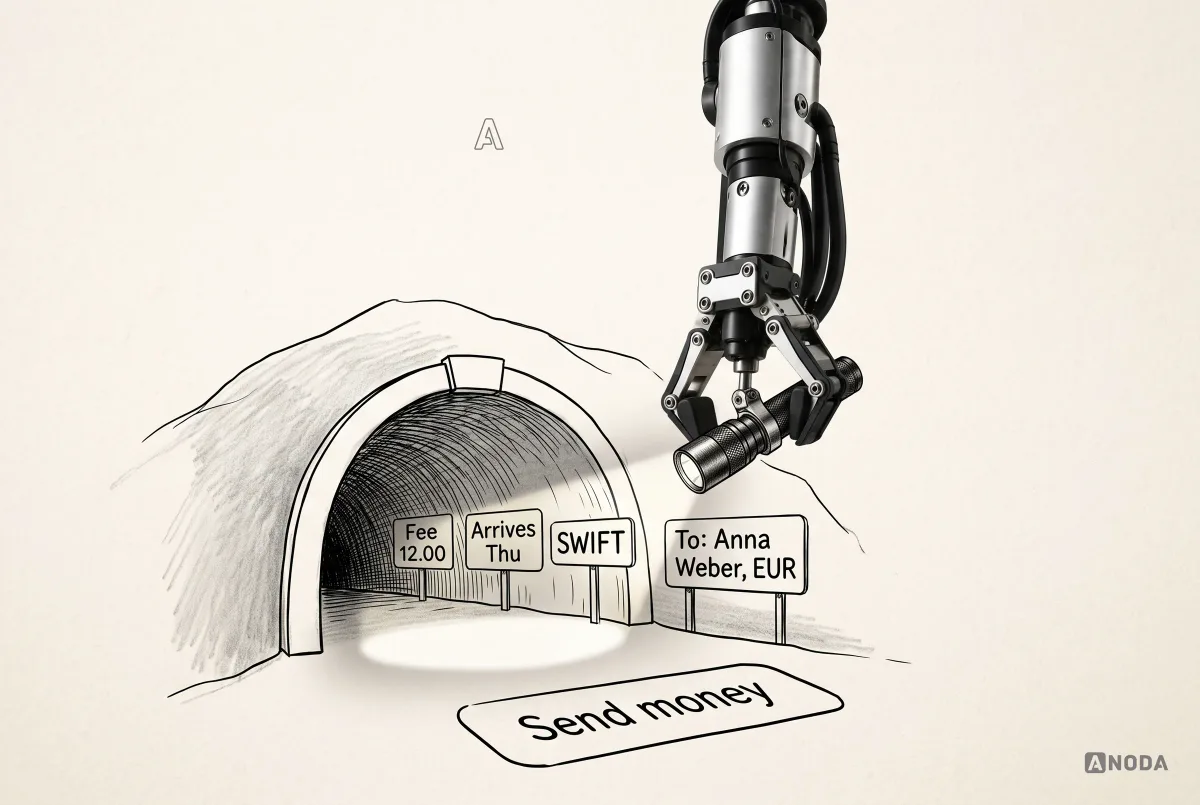
Start with the amount step. When the currencies differ, show both sides live as the user types: what they send and what the recipient receives, with the fee and rate beside it. Nobody should discover the exchange rate on a statement.

Then the review screen. This is the last honest moment before money leaves, and it deserves its own screen, not a pop-up with a single “Confirm” button.


Oksana calls this double confirmation: the user sets the payment up, then reviews and confirms it explicitly. It is not about making people click twice. It is about making sure that the second click happens with every consequence on screen. A confirmation without consequences is theatre. A confirmation with them is protection.
Two details are routinely skipped and routinely regretted:
- The recipient check. Where the product can verify the account holder’s name, say clearly when it does not match, and let the user fix it before the money goes. A mismatch shown after sending is a mistake with a paperwork trail.
- The edit path. The review screen should let the user change any part of the payment without starting over. If editing the amount means re-entering the recipient, users will guess instead.

Audit check
For every payment type, list what the user sees before confirming: amount, fee, rate, total, recipient, currency, type and arrival time.
Failure evidence
Fees shown only on the receipt. Arrival time missing. A single “Confirm” dialog with no summary.
Correction pattern
Add a full review screen for every money movement, show both sides of a currency conversion and make every element editable from the review.
SWIFT, SEPA, ACH: explain the jargon in one line
Transfer types matter to the user, because they decide how fast the money arrives and how much it costs. The names do not help. SWIFT, SEPA, SEPA Instant, ACH, wire, Faster Payments — an alphabet soup that the bank’s staff understand and most customers do not. Oksana is candid that not everyone knows what a SWIFT, SEPA or ACH transfer is, and nobody should have to.
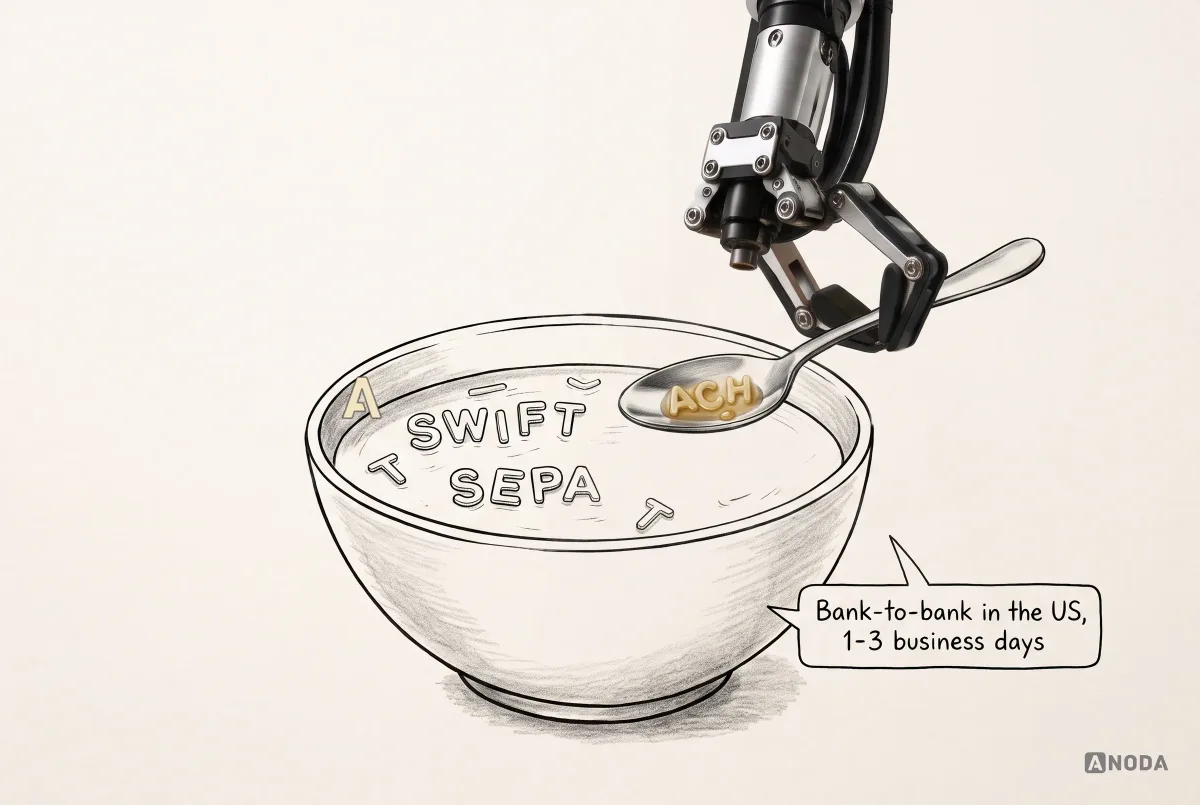
Nacha explains that ACH can process on the same business day or be scheduled for the following or second business day. Your arrival estimate must reflect the product’s actual rail, submission time and processing arrangement. The fix is not a glossary page nobody opens. It is a short explanation right where the choice is made: what this type means for the user, how long it takes and what it costs. Three lines, in the user’s language, one tap away.

When the product offers several transfer types, present them as choices with consequences, not as technical labels. “Instant, arrives in seconds, 0.50” is a decision. “SEPA Instant Credit Transfer” is homework.

Currency exchange: “you give” and “you receive”
Here is a confession that will sound familiar to anyone who has stood at an airport exchange desk. Oksana admits she still cannot remember the buy-and-sell distinction. When she is leaving a country and wants to change the local currency back, does the bank buy it from her, or does she sell it?
Nobody should need a finance degree to swap money. The answer is to stop talking in trader’s terms and describe the exchange from the user’s side: you give this much of this currency, you receive this much of that one.
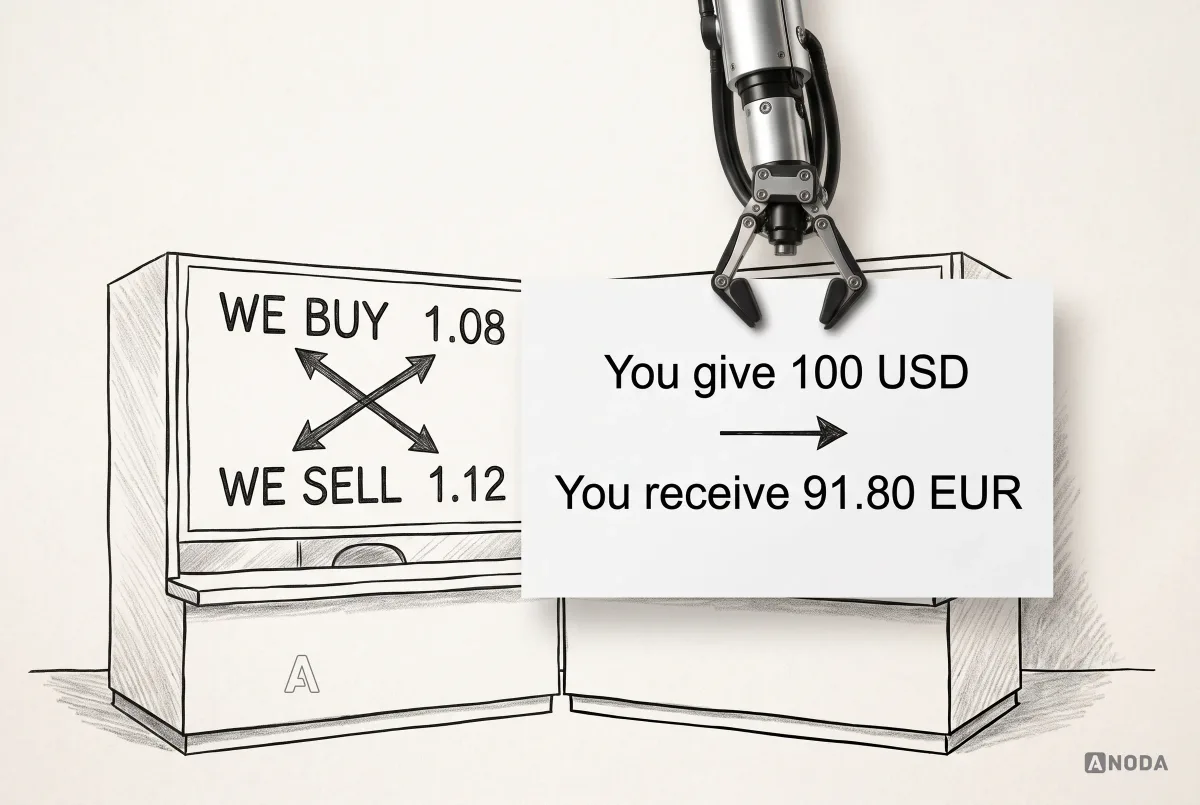

Both currencies, both amounts, the rate and the fee, on one screen. If the rate can move, say how long the quote holds, and when it expires, show the new amount and ask again instead of silently applying it.

We solved a close cousin of this problem for Xcoins, a web and mobile app for buying crypto: the whole buy journey had to show every charge before the confirm button, from the amount the user sends to what they finally receive. The redesign ran to 164 unique screens across web and mobile, and it rests on exactly this principle: the quote you see is the price you pay.
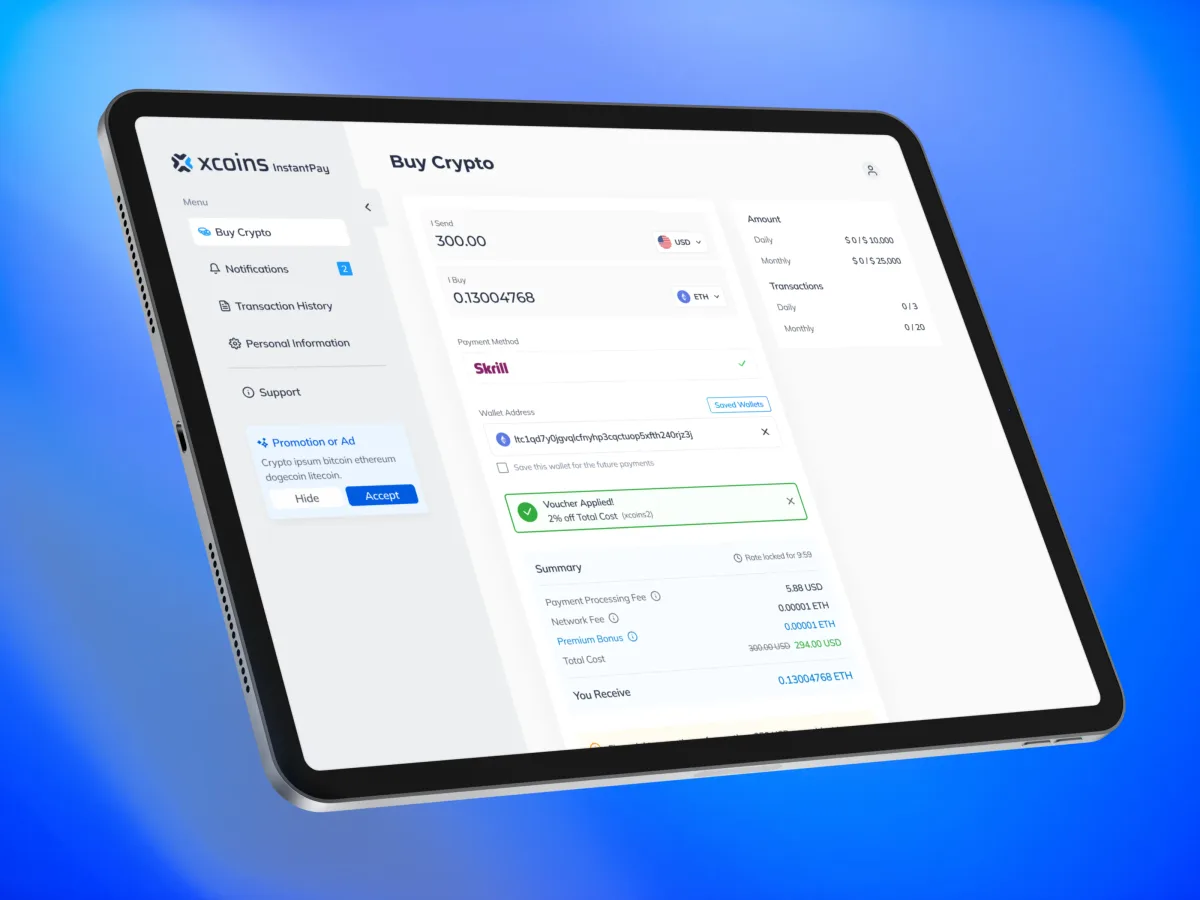
Read how it was done in the Xcoins case study.
The eight states of a payment
A payment is not an event. It is a process with states, and each state needs its own honest screen. Most apps design two: the form and the green tick. Everything else — the in-between, the failure, the reversal — gets a generic message or nothing at all. That is like a lift that shows floors one and ten and nothing in between, then stops between floors with the display blank.
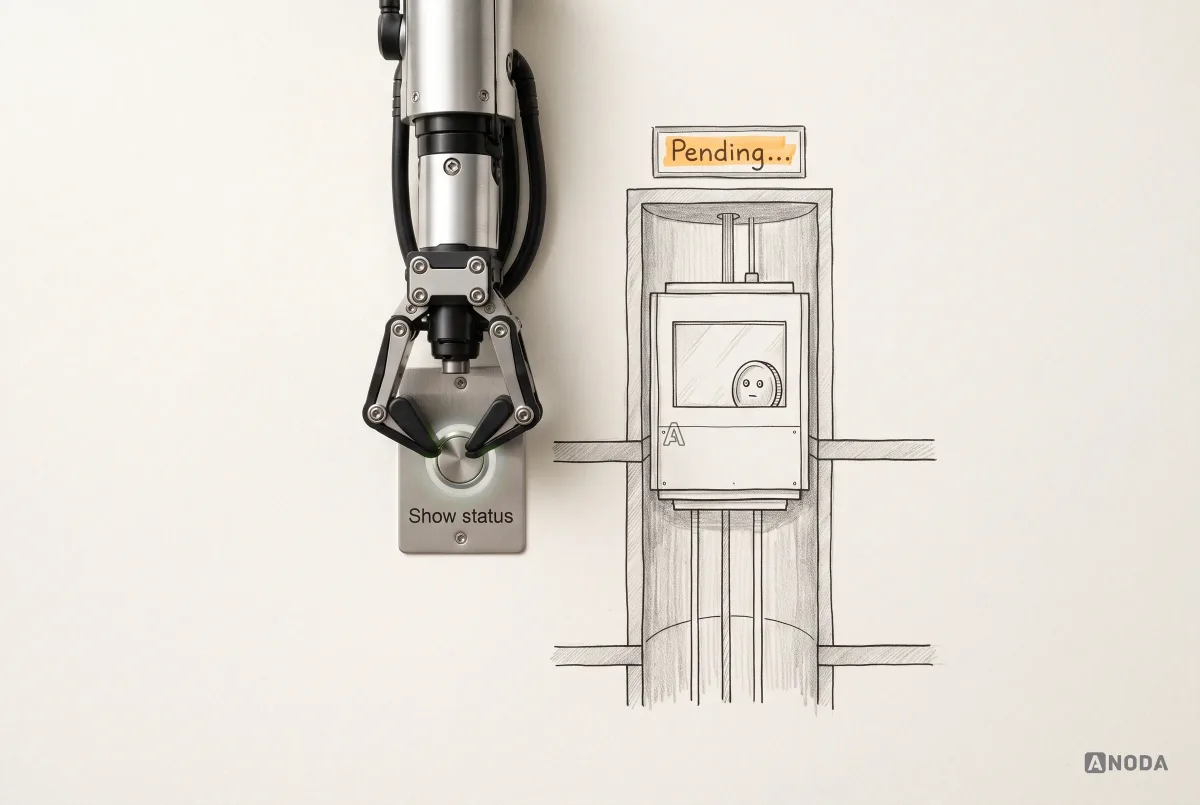
Here are the states every money movement can be in, and what the user needs from each.
| State | What the user needs to know | What they can do |
|---|---|---|
| Before action | Everything that will happen: amount, fee, rate, recipient, arrival | Edit, confirm or cancel |
| Processing | That it is in progress and whether closing the app matters | Wait, or leave safely |
| Success | That it is done, what the recipient gets and when | Save or share the receipt |
| Pending | Where the money is and when it is expected | Track it, or ask about it after the expected date |
| Failed | That nothing was taken, or when it will be returned, and why it failed | Fix the cause and retry |
| Reversed | That the money came back, how much and whether fees were refunded | See the details, send again |
| Blocked | That it was stopped to protect them, and what is needed | Verify, or cancel |
| Requires review | That a check is happening, how long it usually takes, whether money is held | Provide a document, or wait |

Processing is the most neglected state. If it takes more than a moment, say so, and say what happens if the user leaves. “Don’t close the app” is a threat. “You can close the app; we’ll finish and notify you” is a service.


Pending is where trust is quietly spent. A payment that is pending for days needs a location (“with the recipient’s bank”) and an expectation (“expected Thursday”). Without them, “pending” means “we have no idea”, and the user fills the silence with worst cases.

Failure and reversal need the most care, because the user’s first question is not “why?” It is “where is my money?” Answer that first, then the reason, then the fix.


Blocked and under-review states are where banking products most often sound like a police statement. They do not need to. A block is usually protection, and it can be explained as such.


Every completed payment should also leave a clean receipt: amount, recipient, date, reference, and a way to share it. It is the document people need when the landlord says the rent never arrived.

Audit check
Trigger every state for your main payment types — including failure, reversal, block and review — and screenshot what the user sees in each.
Failure evidence
“Processing” with no time frame. One generic error for every failure. Blocks that read like accusations.
Correction pattern
Design a screen for each of the eight states, answer “where is my money?” first and give every state a next step.
Bill payments and scheduled payments
Scheduled and recurring payments trade one moment of attention for months of trust. The user sets them up once and expects the app to behave like a reliable assistant, not like a trapdoor.
Every failed direct debit is a late fee for your customer and a support call for you, and both of them remember whose app said nothing. That means saying exactly what will happen and when: the amount, the frequency, the next date, and what happens if the balance is short on the day. A reminder two days before a payment that will fail is worth more than a polite apology afterwards.

When a bill payment does fail, the message should tell the user what they need to fix and how fast. “Payment unsuccessful” is not a message. “Couldn’t pay Electric Co — you’re 18.40 short. Add money or pay later today” is a plan.

Card controls without guesswork
Card controls are some of the most used features in modern banking apps, and some of the most anxious moments. The user is usually tapping them because something feels wrong: a card left in a taxi, a charge they do not recognise, a trip abroad.
The biggest trap is ambiguity between freezing and cancelling. Freezing is reversible and instant. Cancelling is permanent and means a new card and new details everywhere. One is putting the dog in the other room while the guests arrive. The other is giving the dog away. A customer who cancels by mistake does not blame themselves; they blame you, then spend an evening re-entering card details on every subscription they own — and a few of those subscriptions will quietly move to another bank’s card. Users in a panic do not read small print, so the difference must be in the button labels themselves.

A frozen card should explain what it stops and what may still settle. Monzo’s frozen-card guidance shows why “every payment stops” is too broad: some previously authorized, offline or recurring transactions can still be processed. State your issuer’s actual behavior and distinguish the card freeze from cancelling a subscription or blocking the account. Toggles for online payments, contactless and use abroad should each describe their effect, not just their name.
Limits follow the same principle. When the user changes a limit, show when the change applies and what it affects. Revealing card details needs a quick authentication and a clear way to copy the number, because people are usually doing it with a checkout page open.


Alerts and suspicious activity
Security alerts have one job: help the user act quickly and correctly. Many do the opposite. They shout in capital letters, demand a phone call and leave the customer shaking in a supermarket queue. It is the smoke alarm that goes off every time someone makes toast: after the third time, people take the battery out.
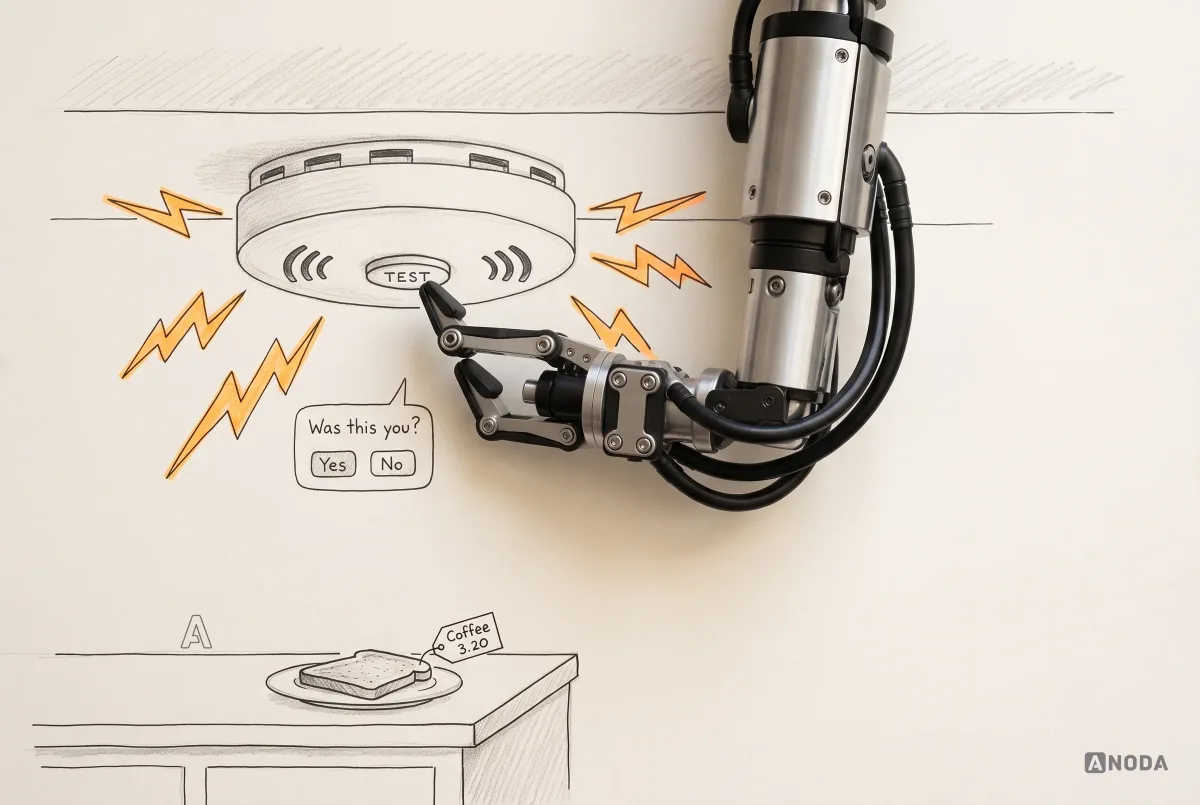
A good alert says what happened, asks a simple question and offers the two obvious answers. “Was this you? 399.00 at TechStore Online, 14:02 — Yes, it was me / No, freeze my card.” The customer answers in one tap, and the bank gets the information it needed.


Let customers choose what they are alerted about: money in, money out, large amounts, declined payments, security events. Alerts people chose are alerts people read.

Audit check
Trigger every alert type and read it as a stressed customer on a small phone. Can they act in one tap?
Failure evidence
Alerts in capital letters. “Call us immediately” as the only action. No way to confirm or deny in the app.
Correction pattern
Rewrite each alert as what happened, one question and two actions, and let customers set their own alert preferences.
Security that people can live with
Banking needs security. Nobody argues with that. The argument is about how it feels. Oksana’s complaint is one every customer will recognise: constant password requests, when biometrics have existed for years. There is no need to demand a PIN, then biometrics, then a password, then an email code, for a 5.00 top-up.
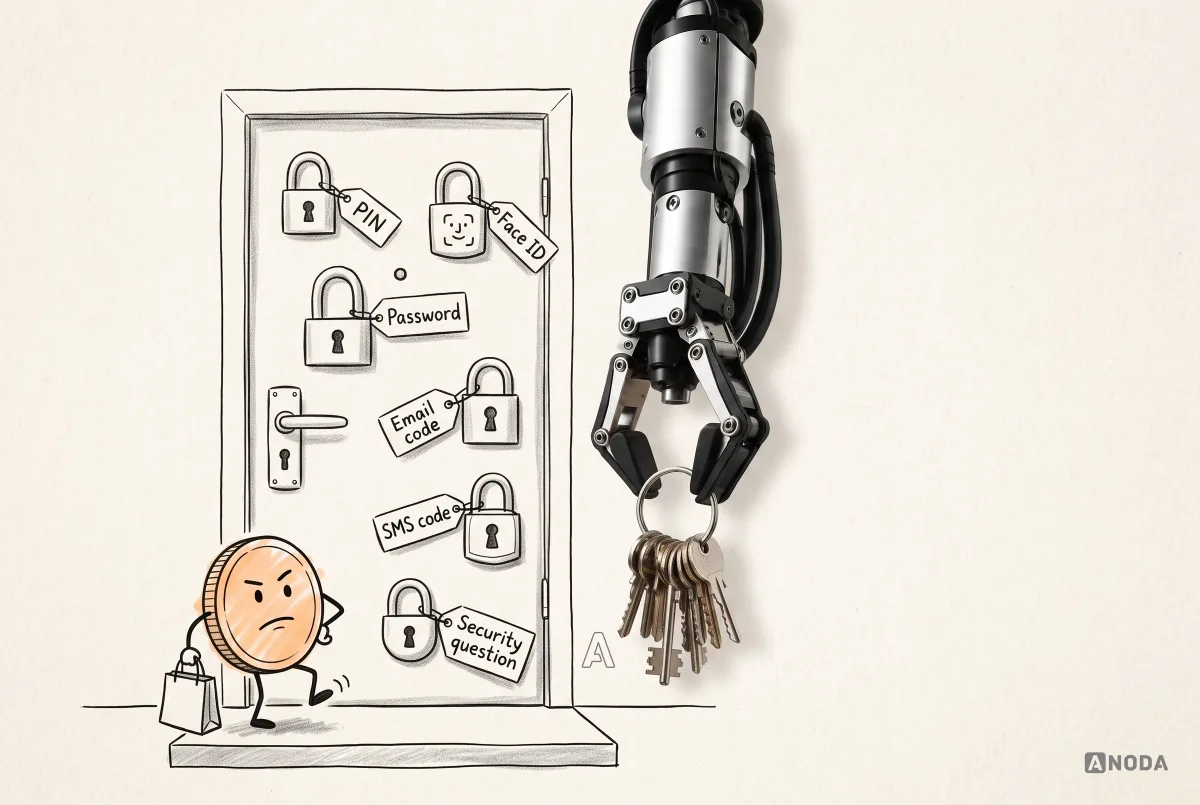
Stacking every mechanism does not make an app safer in the customer’s eyes. It makes it tiring, and tired people take shortcuts: they write PINs on sticky notes, reuse passwords or simply stop using the app for anything that matters. It is penny wise and pound foolish.
A sensible balance looks more like this:
- A quick, familiar way in. Biometrics or a PIN to open the app, as the platform allows.
- Step-up checks where the risk rises. A new recipient, a large amount, a change of contact details, a new device. Explain why the check appears: “We ask because this is your first payment to this account.”
- No repeated checks for the same risk within a session, unless something changes.
- A recovery path that does not punish the honest user. Forgotten PINs and new phones happen. Say how long recovery takes and that cards and payments stay intact.


Timeouts deserve the same respect. Signing an inactive user out is reasonable. Throwing away their half-finished transfer is not. Tell them why they were signed out and that their draft is waiting.


Agree authentication rules and risk triggers with your security, fraud and compliance teams. ANODA makes those controls understandable in the journey: a clear reason for the check, the right moment to ask and a usable recovery path.
Audit check
Count the authentication steps in your five most frequent tasks and in your five riskiest ones.
Failure evidence
The same number of checks for a balance check and a new international payee. Signed-out users losing their drafts.
Correction pattern
Agree risk levels with your security team, apply step-up checks only where risk rises, explain each one, and keep drafts through timeouts.
Fintech product design
Your customers should never wonder where their money is.
We design banking and fintech products where every payment explains itself, every check has a reason and every failure has a way back.
Compliance checks without the red siren
Some money movements touch compliance: large transfers, unusual patterns, certain destinations, the source of funds. The bank may need to ask more questions or pause a payment. That is normal. What is not normal is how many apps handle it — with a huge red warning, capital letters and the implication that the customer has done something wrong.
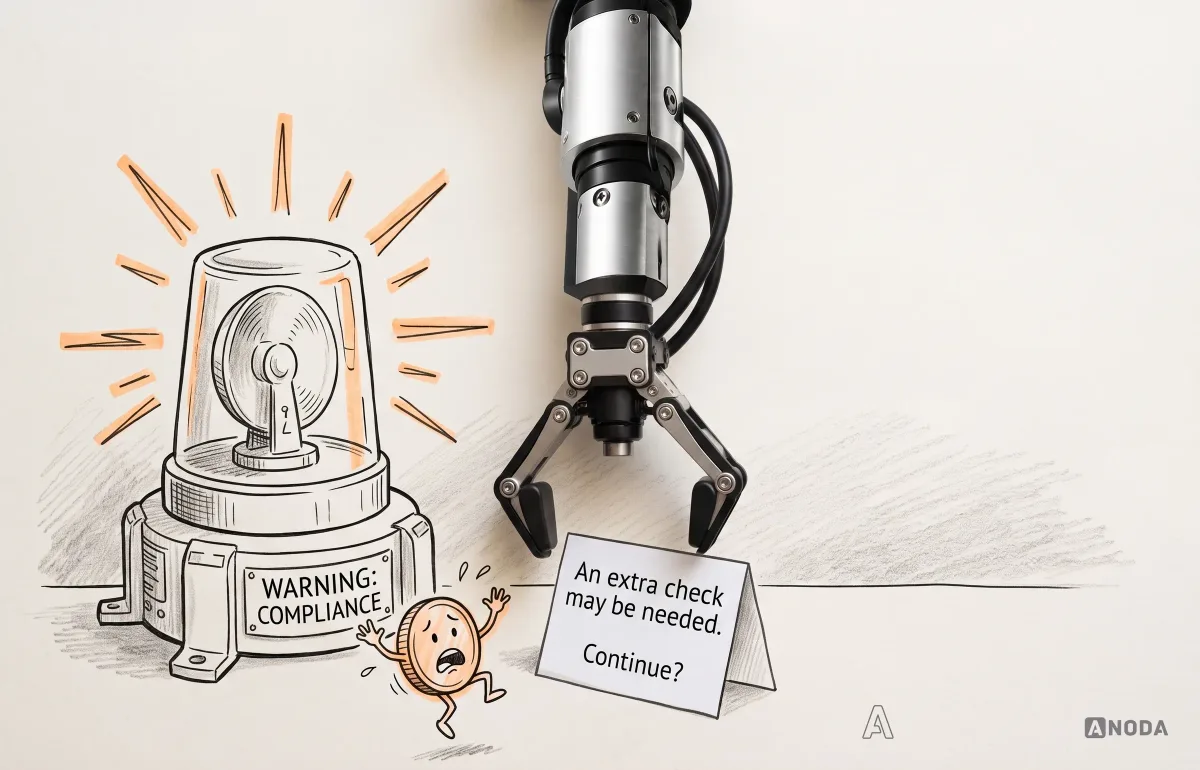
Oksana’s rule is to tell people in advance and let them choose. When an action may trigger additional verification, say so calmly before they start: what might be asked, why and how long it usually takes. Then give an explicit choice: yes, I want to continue, or not now.

When the bank does need more information, explain the question. “Where is this money from?” feels intrusive on its own. With one line about why the bank asks and what happens next, it becomes a routine step.

And once a payment is under review, the review state should do what every good status does: say how long it usually takes, whether the money is held and how the customer will be told.

The legal content — what must be asked, when a payment must be held and what must be disclosed — comes from your compliance team and your regulators. The design job is to make that content clear, calm and timely.
AI in banking apps: say where the data goes
Banking apps are adding AI assistants, spending insights and chat. Oksana calls banking with AI “a separate and very painful topic”, and the pain is not the model. It is the data.
Customers are nervous about sharing financial data with anything that smells of a general cloud. They worry that their transactions will train someone’s model. Some even worry about the tax office knocking on their door tomorrow. Whether or not those fears are accurate for your product, they are real, and an assistant that ignores them will be ignored in return.
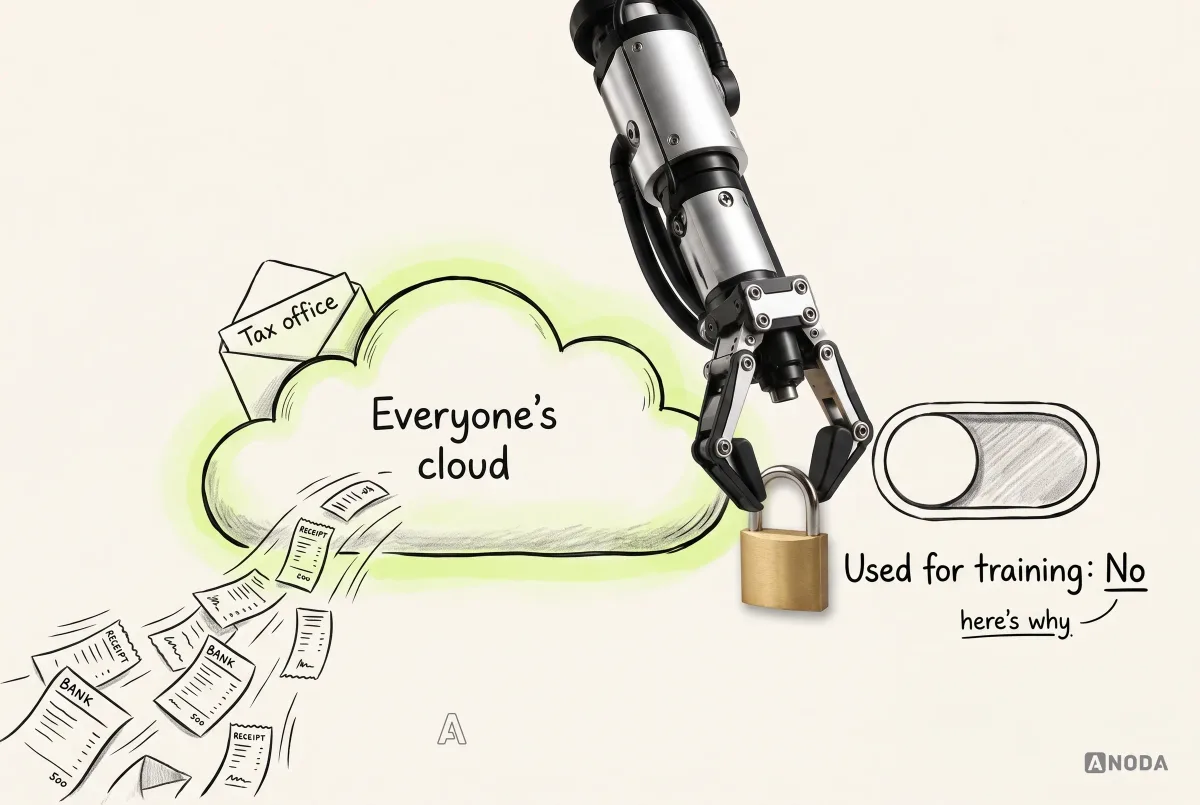
So say it. Before the first interaction, and one tap away afterwards, the product should explain what the assistant can see, what it cannot, whether the data is used to train models and how to switch the feature off. This must describe your actual architecture. If your data does leave your systems, say where and why. A vague promise that is not true is worse than no promise, and it is the fastest way to turn a nervous customer into an angry one.

AI answers about money also need a source. “You spent 312.40 on groceries in September” is only useful if the user knows it is based on two of their three accounts. Without the basis, one wrong number destroys trust in all the right ones.

The same principles we apply to any AI feature apply here, only with higher stakes: decide which job the assistant does, give it the right context, show uncertainty and give every failure a next step.
Errors, disputes and the way back
Every banking app fails sometimes. Declined payments, limits, network timeouts, rejected account numbers. Many products answer all of it with the same shrug: “Error 402. Transaction failed.” That is a doctor who looks at the X-ray, says “something is wrong” and leaves the room.

A useful error message answers three questions: is my money safe, what happened, and what can I do now. “Payment declined — you’ve reached today’s 500 limit. Raise your limit or pay tomorrow” answers all three.
When the problem is not a technical error but a disputed payment, the way back often hides behind four menus. The user has to find the help centre, then the contact page, then the right form, then describe the transaction the app already knows about.
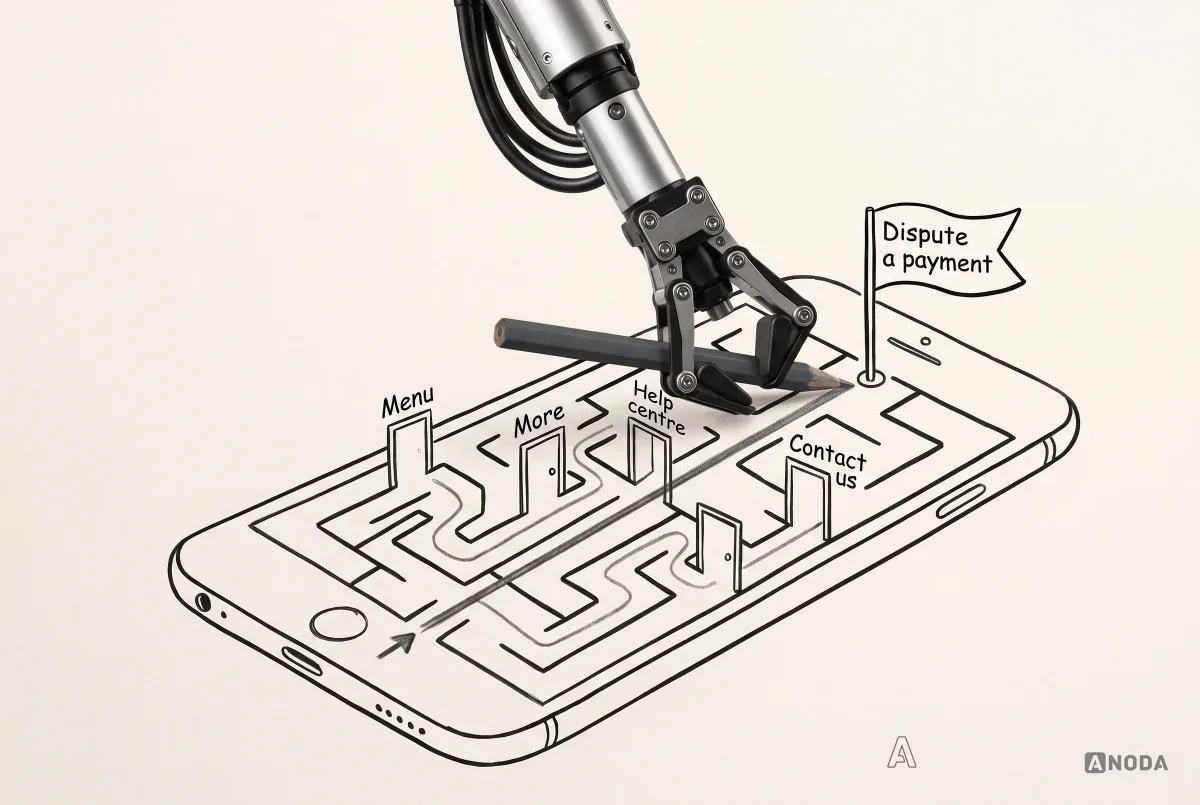
Put the entry point where the doubt appears: on the transaction itself. “Something wrong with this payment?” at the bottom of the transaction detail. Then show the dispute’s progress like any other status, with steps and dates.


When the customer needs a human, the conversation should start with the context already attached. Nobody should have to read out a transaction reference to a chat window that could see it all along.

Audit check
Trigger your most common errors and try to dispute a transaction from scratch, counting the steps.
Failure evidence
Error codes shown to customers. Disputes that start in a generic contact form. Support chats that ask for details the app already has.
Correction pattern
Rewrite each error around safety, cause and next step, add dispute entry to transaction details and pass context into support.
Accessibility is part of trust
People who rely on larger text, screen readers or colour-independent cues have money too. For them, an inaccessible banking app is not an inconvenience. It means asking someone else to read their balance.
Three failures come up in almost every banking audit we run:
- Truncated amounts at larger text sizes. “1,2…” is not a balance. Layouts must reflow so amounts are always shown in full.
- Amounts that screen readers mangle. “−12.50 EUR” should be read as a meaningful phrase — minus twelve euros fifty, card payment, merchant, pending — not as a string of symbols.
- Colour as the only signal. Green for money in and red for money out fails for many people. Add a sign, a word or an icon.


Accessibility requirements for financial services differ by market, and your legal team knows which ones apply. The design principle is the same everywhere: if a customer cannot read the number, the number does not exist for them.
How to test and measure banking app UX
Banking products are often measured by what is easy to count: downloads, logins, monthly active users. None of those tells you whether people understand what is happening to their money. It is judging a gym by how many memberships it sold in January. The numbers look great. Nobody is getting fitter, and in March the direct debits start bouncing.
Test the journeys that carry risk, with real tasks, not opinions. Give participants a job — send money abroad, freeze a card, dispute a payment, recover a forgotten PIN — and watch where they hesitate, what they misread and what they expect to happen.

Then measure what matters in the live product:
- Task success. Did people complete the transfer, the freeze, the dispute?
- Time and error patterns. Where do frequent journeys slow down, and where do people go back and change their input?
- Status comprehension. Can people explain what “pending” or “in review” means for their money? Ask them.
- Recovery success. When something fails, how many people complete the task afterwards?
- Accessibility. Can people complete the key journeys with larger text and assistive technology?
- Support escalation. Which screens generate calls and chats, and about what?
- Behavioural adoption. Do people come back to the feature for the same job, or do they use it once?
There is no universal benchmark that says a good banking app has a certain completion rate or a certain number of support calls per thousand users. Anyone who quotes one without knowing your product is selling something. Set your own baseline, then improve against it.
Why banking apps start with a UX audit
Almost every banking project we take on starts with a UX audit, and not because we like selling audits. It is because, as Oksana puts it, even our team does not fully understand the user’s flow until we have mapped it — and we have built more than ten banking apps for enterprise and consumer products.
Every banking product is different underneath. One adds crypto, another adds stocks, a third is launching an AI assistant, a fourth serves children and parents. The same “best practices” land differently in each. Redesigning screens without understanding the whole journey is repainting one room before anyone has checked the wiring behind the plaster: the room looks lovely right up until the lights go out.
A banking UX audit maps the complete flow, follows each money movement through all its states, checks every security and compliance touchpoint and finds where users lose context, control or confidence. The output is a prioritised list of fixes, ordered by the money and trust they protect. Our UX audit service does exactly that, and it is the fastest way to find out whether you need a redesign or a few precise fixes.
For teams that also need the wider mobile experience rebuilt end to end, mobile app design is the next step after the audit. And if you are looking for what is changing in the category this year rather than the evergreen principles, read our overview of banking app design trends.
Redesign or fix: the decision rule
Not every banking app needs a redesign. Some need three precise fixes and a week of copywriting. Others are so tangled that patching screens is a band-aid on a bullet wound. Ask these questions in order:
- Does the app look maintained and fit its actual audience, or does it look abandoned or aimed at someone else?
- Can users complete your five most important journeys on a phone without losing progress?
- Does every money movement show the full consequences before confirmation?
- Does every payment state have an honest screen and a next step?
- Are security checks proportionate and explained?
- Are compliance checks and AI data handling disclosed calmly and truthfully?
- Do you measure task success, status comprehension and recovery, not only logins?
If the answers fail at one or two points, fix those. If they fail across the board, the problem is the product structure, and a redesign built on a proper audit will cost less than years of patching.
A banking app earns trust when it looks maintained, speaks to its actual audience, saves the user’s progress, explains every financial consequence before confirmation and applies security friction deliberately. Show money movement as “you give” and “you receive”. Make fees, timing, recipient, currency and transfer type explicit. Explain extra verification without frightening anyone, and say clearly how AI uses — or does not use — financial data. And start with an audit of the whole journey before you redesign a single screen or add another feature.
Banking UX audit
Find out where your banking app loses people’s trust.
We map every journey, every payment state and every security check, then hand you a prioritised plan your team can ship.
Frequently asked questions
What makes banking app UX trustworthy?
Four things, and none of them is a navy colour scheme. The app shows accurate status in plain words, including pending, failed and reversed states. It shows every consequence of a money movement before confirmation: amount, fee, rate, recipient, currency, transfer type and arrival time. It applies security checks where the risk actually rises. And when something fails, it says whether the money is safe and what to do next. An app that also looks maintained and fits its audience earns trust faster.
How should a banking app explain pending, failed or reversed transactions?
Answer "where is my money?" first, then the reason, then the next step. A pending payment needs a location and an expected date, such as "with the recipient's bank, expected Thursday". A failed payment should say whether money left the account or when it returns, why it failed and what to fix. A reversed payment should show the amount returned, the date and whether any fee was refunded. Generic messages like "Processing" or "Transaction failed" leave customers to imagine the worst.
How can security friction remain understandable?
Match friction to risk and explain every check. Use a quick, familiar way in, such as biometrics or a PIN, and add step-up checks only when risk rises: a new recipient, a large amount, a new device or changed contact details. Tell people why the check appears. Avoid asking for the same proof twice in a session, keep drafts when a session times out and give honest recovery times. Which checks are required is a decision for your security and compliance teams; design makes them clear.
Which banking journeys should a UX audit test?
Start with the journeys where money or access is at stake: sign-in and recovery, first-use setup and identity checks, balances and transactions, transfers and payments, currency exchange, card controls, alerts and suspicious activity, disputes and support, and session timeouts or interrupted actions. For each one, the audit follows every state, not just the happy path, and records where people lose context, control or confidence. The result is a list of fixes ordered by the money and trust they protect.
When should a team redesign rather than patch isolated screens?
Patch when problems are local: one confusing error, one missing fee line, one alert that shouts. Redesign when the same problems appear across journeys, when the app looks abandoned or aimed at the wrong audience, when long flows lose progress, or when money movements, states and security checks are inconsistent everywhere. At that point the problem is the product structure, and patching costs more over time. Either way, start with an audit of the complete flow so you know which case you are in.
Written by