In short
Financial app onboarding does not fail because KYC exists. It fails because the passport scan, the permissions and the twelve-field form arrive before the user knows what they get, and because one interruption sends them back to the start. Keep every requirement, change the sequence: show the value, explain each sensitive request, break the journey into resumable steps, design the waiting and the rejections, and measure activation — not sign-ups.
In this article
- What financial app onboarding actually includes
- Why financial onboarding is harder than any other
- Define activation before you design a single screen
- Sequence the journey around value, not around the org chart
- Consent and disclosures without the wall of text
- Collect only what each step needs — and explain every sensitive request
- Business onboarding (KYB) is a different journey
- Break the flow into steps people can finish — and resume
- Make funding and account linking feel safe
- Design the hard parts: capture, processing, review and rejection
- After approval: deliver the first value immediately
- Notifications that bring people back
- Build trust before you ask for it
- Markets, documents and languages
- Accessibility is part of eligibility
- Who owns onboarding: product, compliance, security, operations, data and design
- Measure the steps and the whole journey
- Test safely before you roll out
- Common financial onboarding mistakes
- An illustrative example
- How to redesign your financial app onboarding, step by step
Financial app onboarding is the whole journey that takes an eligible person from the promise that brought them in to a verified, secure account they have actually used for something that matters: signup, consent, identity and risk checks (KYC, and KYB for businesses), funding or account linking, and the first meaningful action. It is not a set of welcome screens. It is an activation system — and in finance, the most regulated, most interrupted and most expensive-to-abandon journey in the product.
Here is the part the compliance deck never says out loud: KYC does not kill conversion. Bad sequencing does. The same passport scan that feels reasonable after a user has seen their future savings rate feels like an interrogation when it is the second screen of the app. The same bank-account link that is obvious after a user chose to fund their first goal is terrifying when it appears with no explanation and a logo they have never seen.
Our experience designing and auditing financial products reveals the same costly pattern. The team spends a fortune acquiring a user — ads, referral bonuses, app store work — then asks for the most sensitive data a person owns before showing them anything worth having. A good share of them leave at that exact screen. The acquisition money leaves with them. Every quarter nobody fixes it, the company chooses to keep paying for people who never open an account.
Think of an airport where security asks for your passport, your bank statements, a selfie and a utility bill before you are allowed to see which flights exist. Nobody minds airport security. Everybody minds it when there is no plane.
ANODA connects the promise, verification and first useful action into one journey. We align the sequence with your compliance requirements, design the vendor handoffs and recovery states, and make the approved account useful from the first screen. Your team gets an onboarding experience that earns the acquisition spend instead of sending eligible customers back to the start. FATF’s guidance on digital identity explains the risk-based approach to assessing identity systems for customer due diligence. Use the applicable requirements to set the design boundaries.
What financial app onboarding actually includes
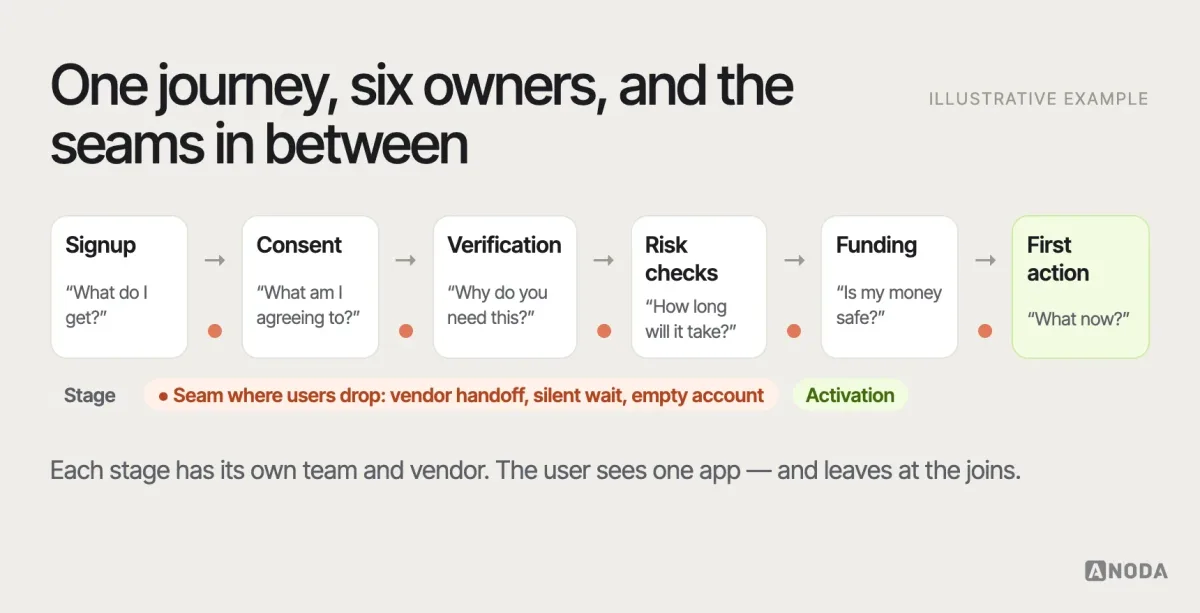
Onboarding in a fintech product is a chain of stages, each with its own owner, its own vendor and its own way to fail:
- Signup and account creation. Email or phone, password or passkey, the first promise of what the product will do.
- Consent and disclosures. Terms, privacy, electronic communications, sometimes product-specific disclosures that must be accepted before anything else.
- Identity verification (KYC) or business verification (KYB). Personal details, document capture, selfie or liveness checks, address, sometimes source of funds.
- Risk and sanctions screening. Mostly invisible to the user — until it isn’t, and an account goes into review.
- Funding or account linking. A card, a bank transfer, an open-banking connection, a direct deposit switch.
- Education and setup. The few things a user must understand to use the product safely: limits, fees, how money moves.
- First meaningful action. The moment the product delivers what it promised: the first payment, the first investment, the first saved amount, the first invoice paid.
Most teams design these stages separately, often with different vendors, and then glue them together. The user experiences them as one journey — and they leave at the seams: between the signup screen and the vendor’s KYC widget, between “documents submitted” and the email three days later, between an approved account and the empty dashboard that follows.
Why financial onboarding is harder than any other
Most product onboarding asks for an email and shows the product. Financial onboarding asks for a legal identity, a document, a face, an address, sometimes an income, and access to someone’s money — from a person who has, at this point, no reason to trust you. It also runs across more parties than any other journey: your app, one or more verification vendors, a risk engine, a banking or payments partner, an operations team doing manual reviews, and support.
Each of those parties has its own latency, its own error states and its own vocabulary. The user sees none of that structure. They see one app that suddenly slows down, asks for something unexpected, or goes quiet for a day. That is why onboarding in finance cannot be designed screen by screen. It has to be designed as a system, with the waiting, the handoffs and the failures treated as first-class parts of the experience rather than edge cases for engineering to handle later.
The stakes are higher too. A user who abandons a note-taking app loses nothing. A user who abandons financial onboarding halfway may have handed over their ID and got nothing in return — which is exactly the kind of experience they tell other people about. A clumsy verification flow can also damage trust beyond the application itself: someone who leaves after submitting sensitive documents has a clear reason to warn others.
Define activation before you design a single screen
You cannot design onboarding until you have decided where it ends. For a financial product, “account created” is not the end; neither is “KYC approved”. Onboarding ends at activation: the first action that delivers the value the user signed up for, done in a way that predicts they will come back.
That definition is product-specific. For a payments app, it might be the first successful transfer to someone else. For a savings product, a first deposit into a goal. For an investing app, a first funded order. For a business account, the first invoice paid or the first card transaction. Agree on it with product, finance and data before any design work, and write down how you will measure it.
Once activation is defined, every design decision gets a test: does this step move an eligible user closer to activation, or does it only move them closer to a compliance checkbox? Many steps must stay because the law or the risk model requires them. But their order, their explanation and their failure paths are design decisions — and that is where most of the money leaks.
Sequence the journey around value, not around the org chart
The default onboarding order in many fintech apps mirrors the internal organisation: legal first, then identity, then risk, then product. It is convenient for the teams. The user meets every cost before any benefit, and the product pays for that backwards sequence in abandoned applications.
A better sequence shows the value first and asks for each requirement at the moment it is needed:
- Show the product and its value before asking for anything sensitive. A preview of the dashboard, a calculator, a sample of the first action. The user should know what they are signing up for.
- Create the account with minimal data. Email or phone and a secure credential. Nothing that can wait.
- Collect what the next step needs, and explain why. If the user wants to see personalised rates, ask for the few inputs that affect them. Before the action that requires verification under the product’s approved rules, explain what the check unlocks and why it is needed.
- Verify identity when the user is motivated. Right before the action that requires it, with a clear statement of what it unlocks.
- Fund or link an account as part of the first action, not as a separate chore. “Add money to your first goal” beats “Link a bank account”.
- Deliver the first value immediately, and make the next useful step obvious.
Whether you can defer verification depends on your regulatory model: some products cannot let a user do anything meaningful before KYC. Even then, you can show the product before the data collection starts, explain precisely what verification unlocks, and make the verification itself fast, clear and recoverable. The requirement stays. The experience around it is yours to design.
The same logic applies after the account is open. Many products need more information later — for higher limits, new features or periodic reviews. Ask for it progressively, when the user wants the thing that requires it, rather than front-loading every possible question into day one. “To raise your transfer limit, we need your source of funds” is a fair trade. The same question on the first screen, for a limit the user may never reach, is just another reason to leave.
Preview the requirements before the user commits
Before signup, explain what this product will ask for: eligible market, supported identity documents, any required address or risk information, and where verification or funding may involve a wait. Distinguish a known processing window from a promise the product cannot control. Make the preview specific to this journey so users can prepare rather than discover an unavailable document halfway through.
Keep marketing attribution questions such as “Where did you hear about us?” out of the required path to first value. Campaign measurement should not turn into another compulsory form field. If a voluntary survey is useful, put it after the useful outcome and let people continue without answering.
Consent and disclosures without the wall of text
Consent screens are where many financial apps lose the user’s attention for good. Legal text has to be presented and accepted; nobody is arguing with that. But a single screen with four checkboxes and a scrolling block of terms teaches people to tick everything without reading, which is the opposite of informed consent.
Separate what must be accepted to open an account from what is optional, and never pre-tick optional marketing consent. Summarise each document in one or two plain sentences next to the full link: what it covers and why it matters. Present product-specific disclosures — about risk, fees or how money is held — at the moment they become relevant, not in a bundle at signup. Keep a record the user can return to later from their settings. Your compliance team decides the wording, timing and what must be shown; design decides whether a person can actually understand what they are agreeing to.
Collect only what each step needs — and explain every sensitive request
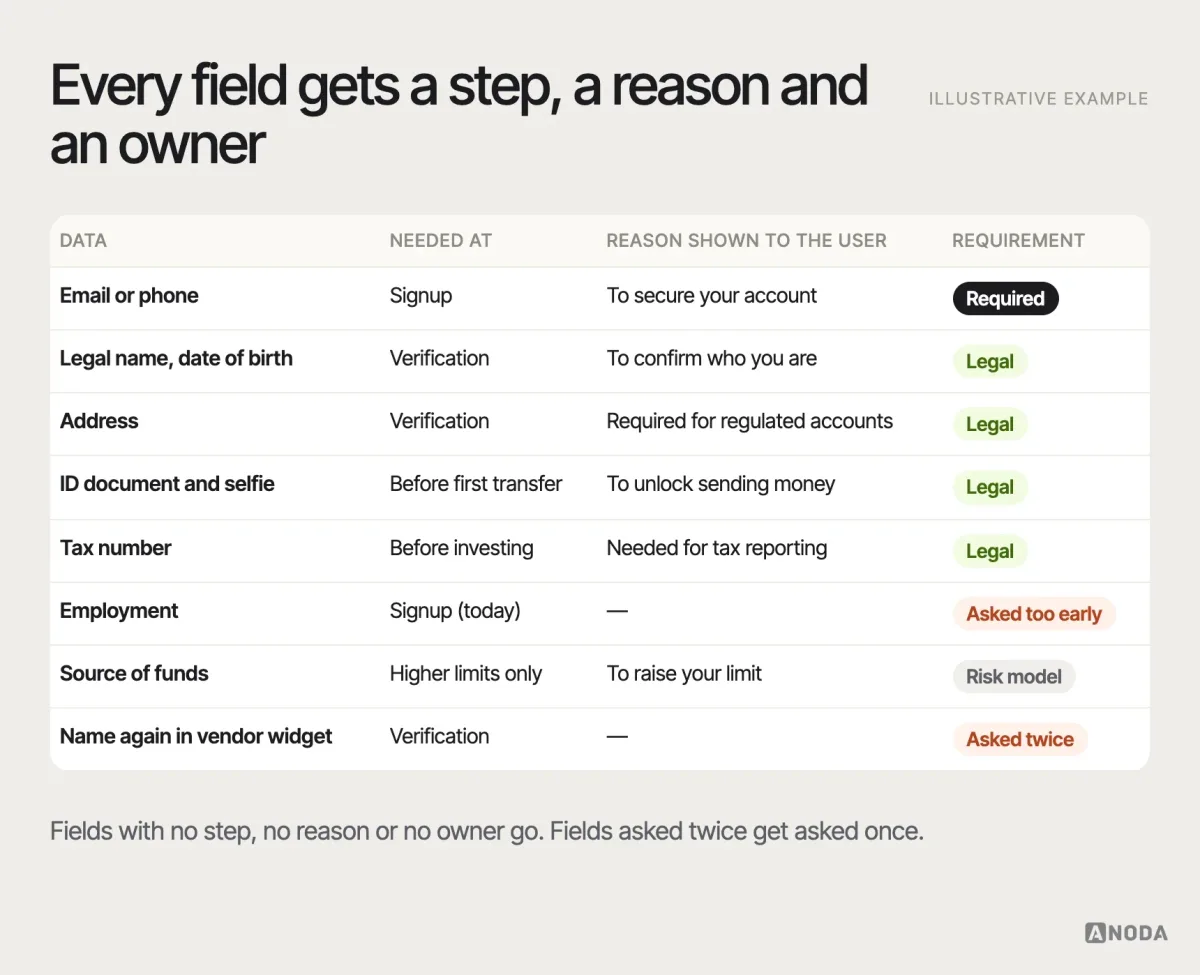
Every field in a financial onboarding flow costs something: time, trust and a chance the user will stop. The question for each one is not “might we need this someday?” but “does the next step need it, and can we explain why?”
Map every data point to the stage that needs it, the reason, and whether it is legally required, required by your risk model, or just nice to have. You will usually find three categories of waste: data asked for too early, data asked for twice (once in your form, once in the vendor’s), and data nobody uses.
Then explain the sensitive requests in plain language on the screen. Adapt these example messages to the product’s actual requirements, data handling and processing times:
- What you need: “A photo of your ID and a quick selfie.”
- Why: “Financial regulations require us to confirm who you are before you can send money.”
- What happens to it: “Your documents are encrypted and used only for verification.”
- How long it takes: “Usually under two minutes; most checks finish right away.”
- What it unlocks: “After this, you can send your first transfer.”
The same applies to permissions: camera, contacts, notifications, location, access to bank data. Ask in context, right before the feature that uses it, with a one-line reason. A permission request with no reason is a stranger asking for your house keys “just in case”.
Business onboarding (KYB) is a different journey
When the customer is a company, onboarding changes shape. The person signing up is rarely the only person involved: the business may need to name its directors and beneficial owners, upload incorporation documents, confirm its address and activity, and sometimes have several people verify their identities. The person filling in the form often doesn’t have all of that at hand.
Design for that reality. Tell the applicant up front which documents and people they will need, so they can gather them before starting. Let them invite other directors or owners to complete their own verification instead of collecting everyone’s documents personally. Save every partial step, because a business application may take days, not minutes. Show the status of each required item — done, waiting for someone else, needs attention — in one place. And let the company start using the parts of the product that do not depend on full verification, where the regulatory model allows it, so the team has a reason to finish.
KYB is also where plain language matters most. “Ultimate beneficial owner” is a precise legal term and a meaningless phrase to many small-business founders. Explain it in a sentence, with an example, next to the field.
Break the flow into steps people can finish — and resume
Financial onboarding is long even when it is well designed, and people do it on phones, on trains, between meetings, while someone asks them a question. They will be interrupted. The only question is whether the interruption costs them their progress.
Think of someone working through a thick form while the doorbell rings. With a bookmark, they come back to page four. Without one, they start again — or, more likely, they don’t.
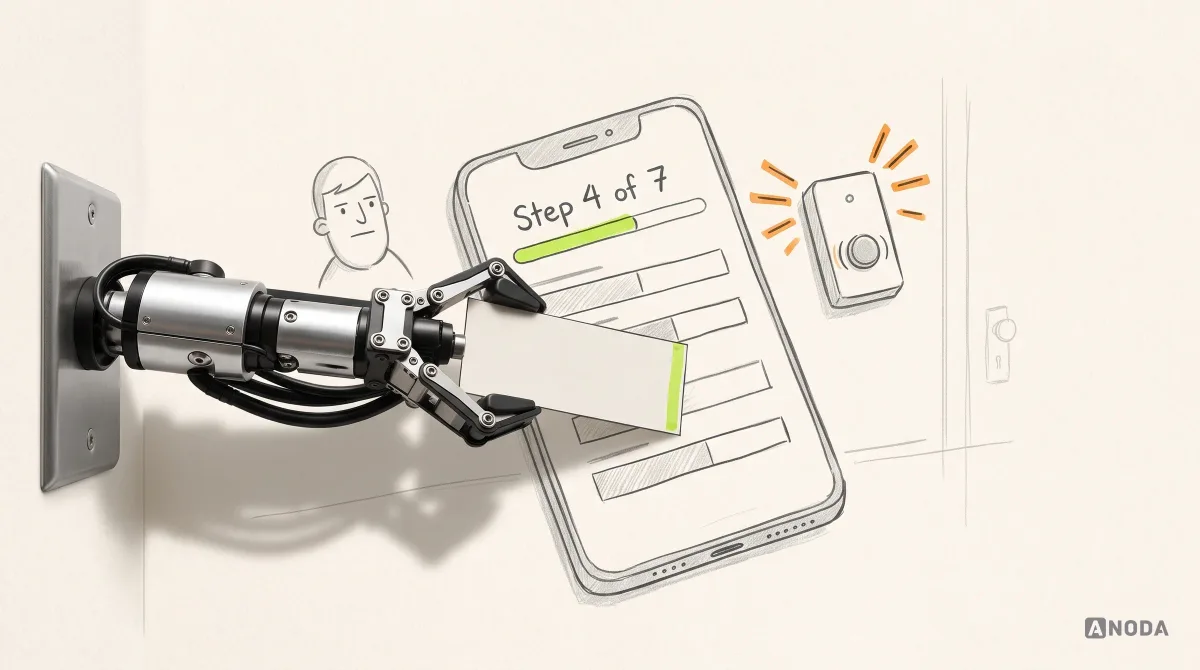
Design for resumability:
- Chunk the journey into short steps with one clear purpose each, rather than one long form.
- Show progress honestly: where the user is, how many steps remain, which ones may take time.
- Save as you go. Preserve completed steps where security and retention rules allow it; explain when a sensitive step must be repeated.
- Resume from any device or channel. A reminder email or notification that takes the user back to the exact step, not to the home screen.
- Let people leave safely. “Save and finish later” should be a visible option, not a trick of the back button.
- Hand off between devices when it helps. If document capture works best on a phone, let a user who started on desktop continue there with a code or link, and bring them back afterwards.
Progress indicators deserve care. A seven-step bar that stalls on step five for two days is worse than no bar at all. Show which steps are instant and which involve waiting, and tell people what happens during the wait.
Make funding and account linking feel safe
Funding is where onboarding becomes real money, and where a second wave of drop-off usually happens. The user has to trust not only your product but also the provider you use to move money or connect their bank.
Give people the options that fit your audience — card, bank transfer, open-banking connection, direct deposit — and explain the trade-offs in a line each: instant or not, fees or not, what access is granted. When you use an account-linking provider, tell users before the handoff that they will see another company’s screen and why; after it, bring them back to a clear confirmation of what was linked and what it can be used for. If the connection fails, keep them in the flow with an alternative method rather than dropping them at a generic error.
Most importantly, make funding part of the first meaningful action rather than a separate chore. “Link your bank account” is a task. “Add money to your first goal” or “Top up to send your first payment” is a reason. The requirement is the same; the motivation is not.
In Blackstar’s investment app, funding had to fit the Ghanaian audience: GHS and USD balances, mobile money and bank transfer, followed by Active or Auto Invest. We designed those routes alongside onboarding and risk questions so the wallet did not become a separate puzzle. See the complete journey and the later responsive website in the case, or explore investment platform design for the broader product scope.
Design the hard parts: capture, processing, review and rejection
Most onboarding designs cover the happy path: document captured, check passed, account open. Real journeys spend a surprising amount of time elsewhere, and those states are where trust is won or lost.
Document and selfie capture. Give clear framing guides, real-time feedback (too dark, glare, move closer), automatic capture when the image is good enough, and a manual fallback. Tell people which documents are accepted before they go looking for one.
Upload and retry. When an image fails, say exactly why and how to fix it. Keep what already succeeded. Two failed attempts should lead to an alternative, not a loop.
Processing. Most checks are fast; some are not. Show a clear processing state with an honest expectation: “This usually takes a minute” or “We’ll email you within one working day”. Never leave a spinner with no explanation.
Manual review. When a case goes to a human, tell the user what is happening, how long it usually takes, whether they need to do anything, and how they will be notified. Let them use whatever parts of the product they safely can in the meantime.
Rejection or failure. Sometimes the answer is no, or not yet. You may not be able to share the exact reason for regulatory or fraud-prevention reasons, but offer the next action permitted for that state: try another document, contact support, wait and try again. A letter stamped “rejected” with no next step is the most expensive message in the product: it turns an applicant into a complaint.
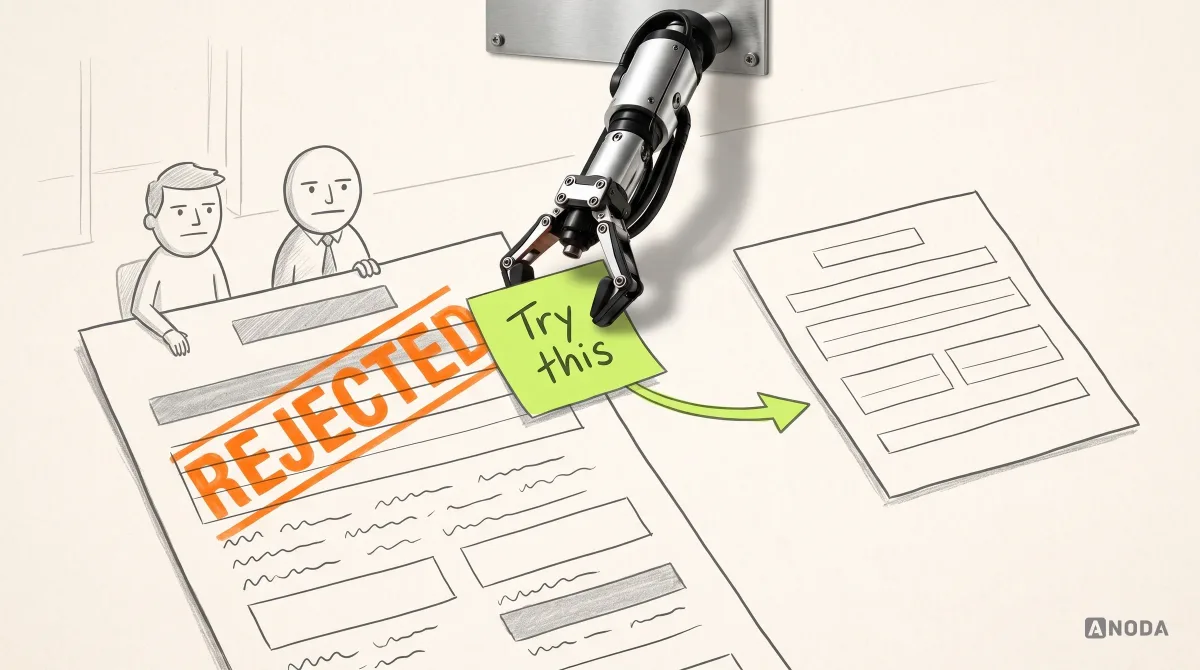
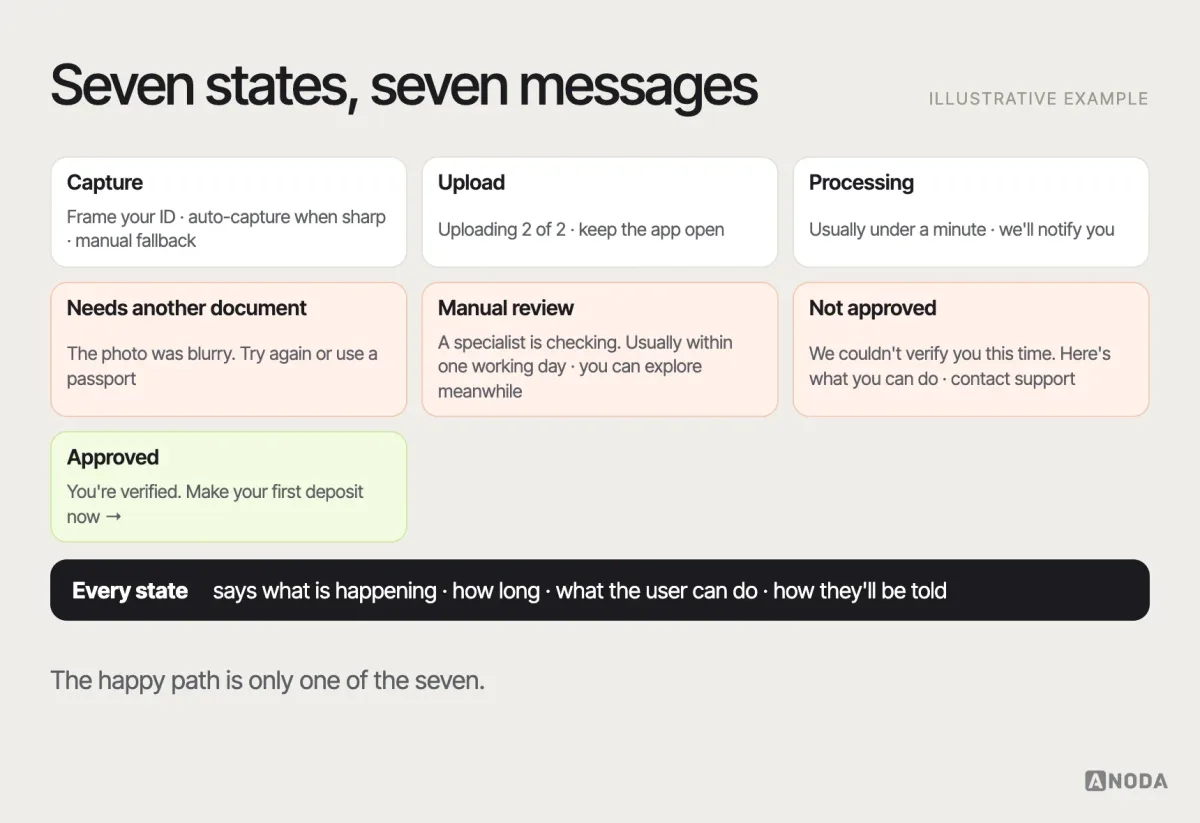
Support paths. Every state that can block a user needs a way to reach a person — or at least a clear answer to “what now?”. Support teams should see the same state the user sees, so nobody has to explain their situation twice.
Activation Audit
Paying for sign-ups that never reach a first transaction?
We trace where eligible users stall between the first screen and the first real action, and show which step, message or missing recovery path is costing you the most.
After approval: deliver the first value immediately
The moment verification succeeds is the moment most onboarding flows forget about the user. The account is open, the team’s funnel says “approved”, and the app shows an empty dashboard with a balance of zero and six menu items.
Treat approval as the start of the most important step. Take the user straight to the action they came for — the goal they created, the payment they wanted to send, the card they wanted to use — with anything they already entered pre-filled. Keep education short and contextual: explain limits, fees or timing at the point where they apply, not in a tour of every feature. And celebrate the first real success in a way that tells the user what they can do next, not with confetti and silence.
If there is an unavoidable wait after approval — a card in the post, a transfer that settles in a day — say so, and give the user something useful to do in the meantime.
Notifications that bring people back
Because financial onboarding is interrupted so often, the messages sent during it are part of the design. Every reminder should take the user back to the exact step they left, say what is left to do and roughly how long it takes, and never pressure with fake urgency. Status notifications for processing and manual review should arrive when the status changes, in the channel the user chose, with a clear next step. And the messages should sound like the product, not like an automated compliance notice — while still being careful never to include sensitive data in an email or push notification.
Build trust before you ask for it
In finance, trust is not a brand value on the About page. It is a sequence of small signals in the onboarding flow, each one answering a doubt the user has at that moment.
- Before signup: who you are, who regulates or partners with you, how money is protected — stated plainly and verifiably, not as a wall of badges.
- During data collection: why each item is needed, how it is protected, who sees it.
- During linking or funding: which provider handles the connection, what access is granted, how to revoke it.
- After approval: what the user can do now, what limits apply, what fees exist, where to get help.
Fees, limits and consequences belong in the flow, not in a PDF. If a transfer takes two days, say so before the user sends it. If a card has a monthly fee after a trial, show it before the card is ordered. People forgive rules they understood. They do not forgive surprises with money.
Security features are part of trust as well, and they are onboarding steps in their own right: setting up a passkey or a strong password, enabling two-factor authentication, binding a device. Explain what each protects against in a sentence, make the recommended option the easy default, and avoid stacking every security measure at once before the user has done anything. Security that people understand, they keep enabled. Security that feels like punishment, they look for ways around.
Tone matters too. Financial onboarding copy often swings between legalese and forced cheerfulness. Neither builds trust. Plain, specific, calm language does: what is happening, why, and what happens next.
Markets, documents and languages
If the product operates in more than one country, onboarding stops being one journey. Accepted identity documents differ, address formats differ, names are written differently, some markets need tax identifiers and others don’t, and verification vendors perform unevenly across regions. A flow designed around one country’s passport and postcode will quietly fail everyone else.
Design the variable parts as variables: the list of accepted documents per country, address fields that follow local formats, name fields that don’t assume a first-and-last structure, and copy that is translated and reviewed rather than machine-translated at the last minute. Measure verification pass rates per market and per document type, because the average will hide the country where half your applicants fail.
Accessibility is part of eligibility
A financial product that some eligible users cannot complete is excluding customers from their own money. Onboarding needs to work with screen readers, keyboard navigation, larger text sizes and reduced motion. Document capture needs alternatives for people who cannot use the camera flow easily. Time limits on verification steps should be generous or extendable. Error messages cannot rely on colour alone. And plain language is an accessibility feature: many users are reading in a second language, under stress, about a regulated product.
Who owns onboarding: product, compliance, security, operations, data and design
Onboarding breaks when every team owns one step and nobody owns the journey. Compliance defines what must be collected. Security defines how it is protected and what counts as suspicious. Operations handles manual reviews and support. Data measures the funnel. Engineering integrates the vendors. Design shapes the whole experience. Product owns the outcome.
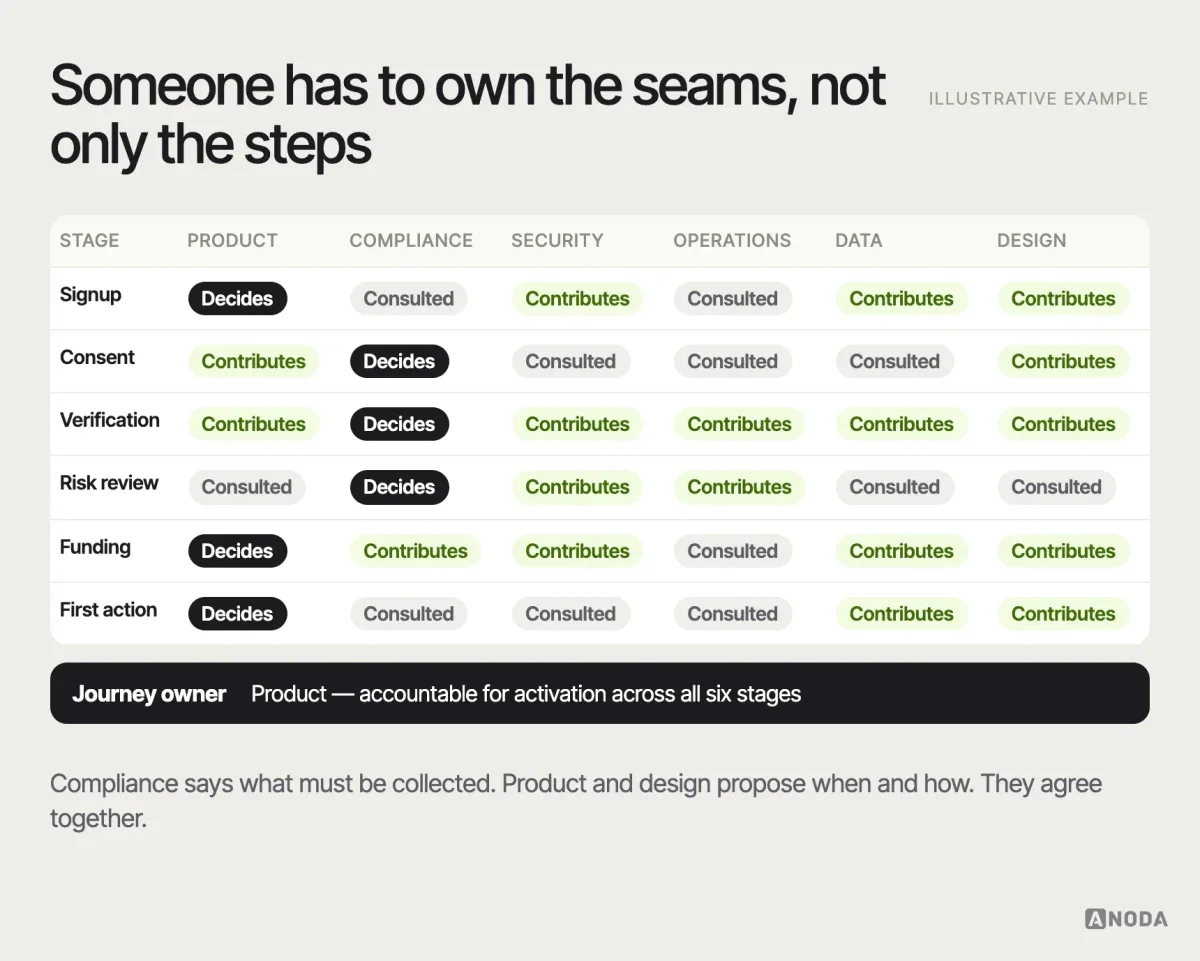
Two practices make this work. First, a single journey owner — usually product — who is accountable for activation, not for any one step. Second, shared decisions on the requirements themselves: compliance says what must be collected, design and product propose when and how, and the three agree together. Most onboarding problems we audit come from requirements that were written in one team and implemented in another, with nobody asking whether they could be sequenced differently.
Measure the steps and the whole journey
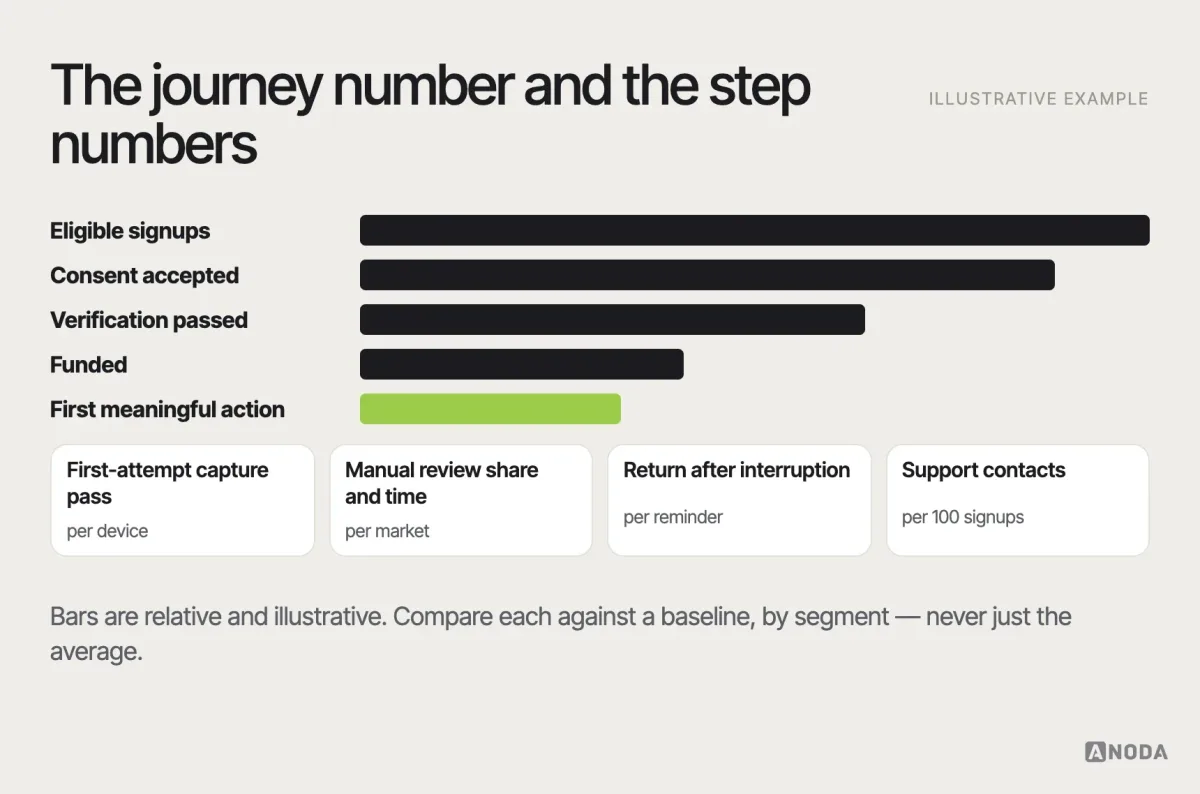
You cannot improve onboarding you do not measure at the right level. Journey-level metrics tell you whether onboarding works; step-level metrics tell you where it doesn’t.
- Journey level: the share of eligible signups who reach activation, and how long it takes them.
- Step level: completion rate and time for each stage — signup, consent, verification, funding, first action.
- Verification quality: first-attempt pass rate for document capture, retry rate, share going to manual review, review time, and the share of legitimate users rejected.
- Recovery: how many users who leave mid-flow come back, and from which reminder or channel.
- Support load: onboarding-related contacts per hundred signups, and their top themes.
Numbers tell you where people stop, not why. Pair them with privacy-safe observations of the verification steps, redacted support themes and a handful of short interviews with people who abandoned and people who finished. The reasons are usually mundane — a confusing document list, a camera that would not focus, a status email that went to spam — and cheap to fix once someone looks.
Segment everything: by device, by acquisition channel, by market, by user type. A verification step that works on recent phones and fails on older ones, or passes in one market and struggles in another, will be invisible in an average. And always separate “didn’t finish” from “wasn’t eligible”: you do not want to “improve” a funnel by weakening the checks that are meant to stop people.
Test safely before you roll out
Changing a regulated journey is not like changing a landing page. Test the design before it touches real applications:
- Prototype and usability-test the full journey with people who match your audience, including the unhappy paths: a blurry document, a failed link, a manual review message.
- Review with compliance and security early, with the prototype rather than a spreadsheet of requirements, so constraints shape the design instead of arriving as late objections.
- Use vendor sandboxes to test capture, retry and failure states with realistic behaviour.
- Roll out gradually — a share of traffic, one market or one platform first — and compare against the existing journey on step and journey metrics.
- Watch the edges: fraud signals, manual review volume and support contacts, not just conversion. A change that lifts completion while flooding the review queue has moved the problem, not solved it.
Include the people most likely to struggle in the tests: users on older phones and slow connections, people using screen readers or large text, applicants whose names or addresses do not fit the default format, and business customers with more than one owner. They are where onboarding failures hide, and they are also where a well-designed flow becomes a genuine competitive advantage — because they are exactly the customers other providers keep losing.
If your team has the requirements and needs the journey and interface designed end to end — from the first screen to the first meaningful action — that is the scope of our UI/UX design work for regulated products.
Common financial onboarding mistakes
The same list appears in almost every audit:
- KYC on screen two. The product asks for identity documents before showing what the user gets.
- Every field up front. One long form that collects data for steps the user may never reach.
- Asking twice. The same data collected in the app and again inside the vendor’s widget.
- No reasons. Sensitive requests and permissions with no explanation of why or what happens to the data.
- Progress that doesn’t survive interruption. Close the app, start again.
- Spinners and silence. Processing and manual review with no expectation of time and no notification.
- Dead-end rejections. “We couldn’t verify you” and nothing else.
- Fees and limits discovered later. The user learns the rules after breaking them.
- An empty account after approval. Verification succeeds, and the product shows a blank dashboard instead of the first useful action.
- Measuring sign-ups instead of activation. The team celebrates the top of the funnel while the bottom stays empty.
An illustrative example
Here is how the approach plays out on a typical product — an illustrative example, not a specific client. A consumer savings app sees healthy install and signup numbers, but only a fraction of verified users ever make a first deposit.
The audit finds that identity verification appears immediately after signup, before users have seen a savings goal or an interest rate. Document capture fails often on older phones, and failures send users back to the start of verification. Manual reviews take a day or two, and users hear nothing until an email arrives. After approval, the app shows an empty balance and a menu.
The redesign keeps every requirement and changes the journey. New users set up a first goal and see how it grows before verification. Verification is introduced as the step that unlocks the first deposit, with a clear explanation and time estimate. Capture gets better guidance and an alternative upload path; completed steps are saved. Manual review shows an honest status with a notification when it finishes. After approval, the first screen is the deposit into the goal the user already created. Activation — a first deposit — is measured by step, device and channel against the previous journey.
The team also changes how it measures success. Instead of counting approved accounts, it tracks the share of eligible signups who make a first deposit within a week, broken down by device and acquisition channel, with the verification first-attempt pass rate and review time alongside.
Nothing about compliance changed. The sequence, the explanations and the recovery paths did — which is exactly where onboarding is usually won or lost. For broader principles around this kind of product, see our guide to fintech user experience; for problems that go beyond activation, a wider UX audit is the right starting point.
How to redesign your financial app onboarding, step by step
- Define activation — the first meaningful action — and how you will measure it.
- Map the current journey end to end, including vendors, reviews, emails and support, and find the seams where users leave.
- List every data point and permission with the step that needs it, the reason and the requirement behind it.
- Resequence around value: show the product first, ask for each requirement when the next step needs it.
- Explain every sensitive request on screen: what, why, how it is protected, how long it takes, what it unlocks.
- Chunk the flow and make it resumable across interruptions and devices.
- Design every verification state, including processing, manual review, rejection and support.
- Put fees, limits and consequences in the flow.
- Agree ownership of the journey and the seams between teams.
- Test safely, roll out gradually and measure steps and the whole journey by segment.
Show the benefit and the requirement together, break the flow into steps people can resume, explain every permission, and make progress and consequences visible. Security and compliance stay exactly where they are. What changes is whether eligible people make it through them.
Fintech design
Compliance says what to collect. Who designs how?
We turn regulatory, security and operational constraints into an onboarding journey eligible users can actually finish — with clear requirements, recoverable verification steps and a first useful action.
Frequently asked questions
What steps belong in financial app onboarding?
Requirements preview, secure access, consent, required identity checks, relevant funding and a useful first action.
When should a fintech app request KYC information?
At the point required for the allowed action, with an explanation and preparation guidance.
How should onboarding explain a failed identity check?
Explain the actionable next step, preserve progress and offer support where needed.
Should financial onboarding allow save and resume?
Where product and security rules permit; show what is saved and how to resume securely.
Which activation metrics matter beyond signup completion?
Successful verified use, time to first value, completion, retries and failure reasons.
Can fintech teams A/B test regulated onboarding?
Test within boundaries agreed with compliance, security and operations.
Written by