In short
A beautiful fintech homepage is the cheapest part of the job. The expensive part is what sits under it: who the product is for, what it costs, what happens to the money if something breaks and which button a cautious buyer should press. The examples use eight buyer questions to explain design decisions you can adapt, rather than copying a famous brand’s gradients.
In this article
- How we judged these fintech website design examples
- What a nervous visitor needs before the first click
- Wise: the price is the product, so the price is the hero
- Stripe: one headline, four audiences, four front doors
- Mercury: the uncomfortable sentence goes next to the button
- Chime: every bold claim carries its receipt
- Monzo: price, eligibility and risk on every card
- Starling: trust from evidence you cannot award yourself
- Brex: numbers with a source and a best-before date
- Plaid: design for the person who never chose you
- Robinhood: good disclosures inside a crowded noticeboard
- Your next reader may be researching with software
- Official sources for the examples
- Which patterns travel and which belong to the brand
- Mobile and accessibility: where fintech trust quietly breaks
- From website promise to the first product screen
- Blackstar: explain the investment product before installation
- How to use these examples without copying them
- The takeaway
The best fintech website design examples are not the prettiest ones. They are the ones that answer a nervous visitor’s four questions before the visitor has to ask them: is my money safe here, what does this cost, is this product for someone like me, and what happens after I press the button. A polished hero answers none of those. It is the wrapping paper. People do not move their salary, their payroll or their company’s cash because the wrapping paper was nice.
In our financial-product design work, we repeatedly see the same kick-off pattern. Someone opens a folder of screenshots: Stripe, Revolut, Wise, Monzo, “something like this, but ours”. The team spends a quarter reproducing a gradient, a floating card and a headline with the word “reimagined” in it. Then paid traffic lands on the new homepage, reads a slogan, finds no price, no eligibility and no word on who holds the money, and leaves. You paid for that click. You will pay for the next one too.
The examples below examine familiar fintech websites through the questions a cautious buyer asks. They show the decisions that reduce hesitation and move buyers toward the right action. For every example you get what the site does, why it works, where copying it would backfire and what you can reuse. The UX decisions matter more than the pixels, which is why the pictures in this article are our own redrawn schematics and illustrations, not screenshots of other companies’ sites.
ANODA turns that anxiety into a clear buying journey. We connect the message, pricing explanation, trust signals and next action with the product behind them, so buyers see a coherent offer rather than another familiar fintech gradient. Blackstar below shows how we bring the website and investment app together.
How we judged these fintech website design examples
Judging a fintech website by its hero is buying a house from the estate agent’s wide-angle photos. The living room looks enormous, the light is golden, and nobody has photographed the boiler, the damp patch or the survey. A fintech homepage has its own boiler: fees, protection, eligibility, the regulated entity behind the product and the path from “interesting” to “approved”.
Use these eight questions to inspect each example:
- Audience and product job. Can a stranger tell in one screen who this is for and what it does for them?
- Trust signals. Is protection, regulation and the legal entity stated plainly, near the decision, in words a customer understands?
- Information architecture. Can each audience find its own path without wading through everyone else’s?
- Complexity management. Is the hard part (pricing, rates, risk, eligibility) explained by showing, not by adjectives?
- Proof. Are numbers, reviews and awards specific, sourced and dated, or just big?
- Conversion path. Does the call to action match how ready the visitor is: browse, compare, try, apply, talk to sales?
- Interaction, accessibility and mobile. Does the site still work at 390 pixels wide, with a keyboard, zoomed in, on a slow train?
- The reusable lesson. What can another fintech team take, and what only works because of this brand’s size or audience?

Notice what is not on the list: colour, illustration style, animation, dark mode, the font everybody bought this year. Those matter, but only after the eight questions have answers. A credible fintech website is not the one that looks most expensive. It is the one where a stranger can find out, within a minute and without talking to anybody, who is responsible for their money, what it will cost them, whether they qualify and what the next step involves. Credibility is the absence of unanswered questions. The visual layer can make those answers feel calm and deliberate, or it can bury them under a hero video. In our audits, the second is far more common, and it is always the more expensive one to fix later, because by then the brand, the campaign and the investor deck all depend on it.
A few ground rules. These sites change weekly and serve different versions by country, so we name the version we saw and the date. A pattern we praise is a decision worth studying, not an endorsement of the company or its product. The observations focus on public product information and navigation. Use the linked regional sources when adapting a pattern to your own market.
Here is the whole scorecard in one table before we go site by site.
| Example and regional context | Who it serves | Strongest decision | Where copying backfires |
|---|---|---|---|
| Wise (UK) | People and businesses moving money across borders | Shows the price and arrival time before signup | If your price is not your advantage, a calculator advertises your weakness |
| Stripe (localized homepage) | Developers, startups, platforms, enterprises | Routes each audience to its own entry path | Scale-based proof looks silly without the scale |
| Mercury (US) | Startups and small businesses | Puts “not a bank” next to the sign-up button | Only works if the disclosure is written for people |
| Chime (US) | Everyday US consumers | Every bold claim carries a numbered disclosure | Footnote soup if the claims multiply |
| Monzo (UK) | Everyday UK consumers | Price, eligibility and risk on each product card | A catalogue homepage needs a brand people already know |
| Starling (UK) | Personal and business customers | Shows independent, regulator-required evidence | Evidence only helps if the results are decent |
| Brex (US) | Companies from startup to enterprise | Dates and sources its headline numbers | Stale numbers age visibly |
| Plaid (EU version) | Developers and the consumers who meet it inside other apps | A path for users who never chose Plaid | Consumers still land in a developer-first site |
| Robinhood (US) | Retail investors | Entity and risk lines beside each product | A noticeboard homepage exhausts newcomers |
| Machine-readable product information | Buyers and the tools they use to research vendors | A plain, accessible summary of the offer | Machines repeat vague copy faithfully |
What a nervous visitor needs before the first click
Think of a school prospectus that has beautiful photos of the playing fields and no inspection report. Parents do not stop worrying; they just go and find the report somewhere else, often on a forum with worse news. Fintech visitors behave the same. Every question the page skips becomes a search, a support chat or a closed tab.
We map those questions before we touch a layout. The order matters. “Is it for me?” comes first, because an ineligible visitor who reads your whole page is a paid click with a sad ending. “Is it safe?” and “What does it cost?” come next, near the decision, not in the footer. “What happens next?” belongs on the button itself. We build every website design project around that order before anyone picks a typeface.
Proof comes after those answers, not instead of them. A wall of logos tells a visitor that other companies signed up. It does not tell them what they will pay or who holds their deposits. We regularly audit fintech homepages with six sections of social proof and not one sentence about fees, and the analytics look exactly as you would expect: long scrolls, short sessions, a support inbox full of questions the homepage could have answered.

Wise: the price is the product, so the price is the hero
Wise’s UK homepage leads with “The current account for home and abroad”, and right under it sits the thing most fintechs hide: a live quote. “You send exactly”, “Recipient gets”, “Arrives”, “Total fees”, with the fee “Included in GBP amount” and a line claiming how much you could save. A note offers a discount on the fee for transfers over 20,000 GBP. No signup, no “request a quote”, no sales call.
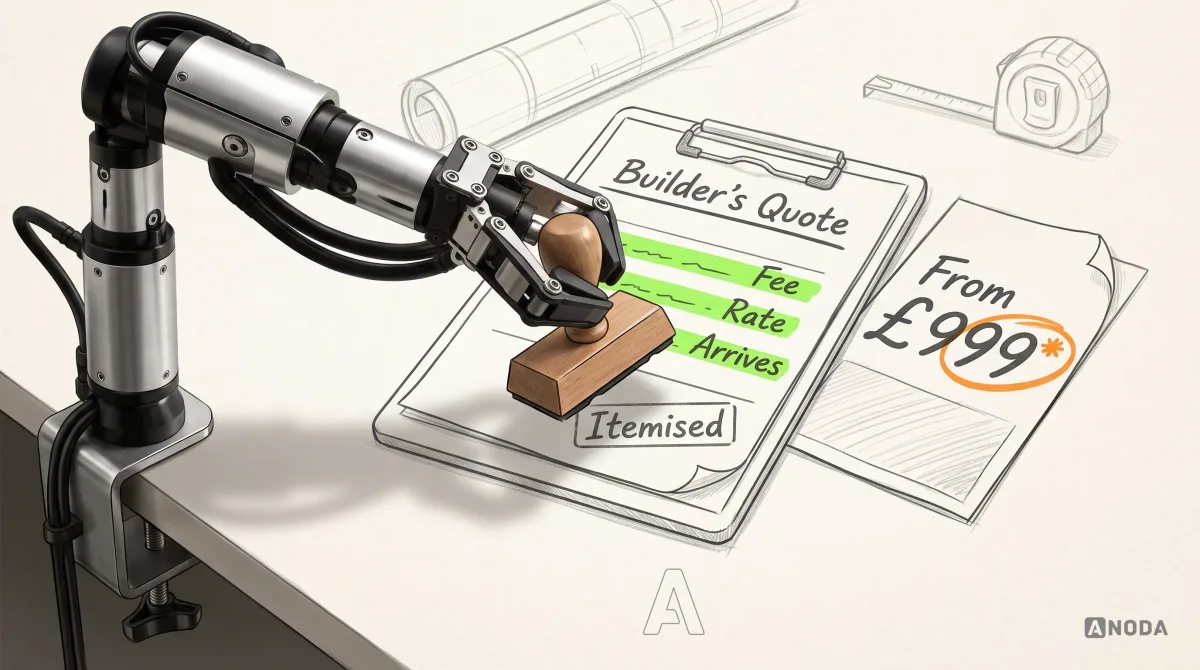
This is a builder’s itemised quote instead of “extensions from £999*”. The itemised quote wins the job even when it is not the cheapest, because the client can see where the money goes. For a transfer product, the fee and the arrival time are the product. Showing them first is not a design flourish. It is the sales pitch, doing the maths in public.

The same page handles a harder moment well. Next to an offer to earn a variable rate on your balance, it says in plain text that money can decrease in value, that current rates do not guarantee future performance, and which date the rate is based on. The risk sits next to the reward, at the same size of attention, not three clicks away.

The safety block is equally plain: safeguarded funds held in a separate account, a count of daily fraud checks, the regulator and firm reference in the footer. None of it is poetic. All of it answers a question someone would otherwise type into a search bar.
What we would still question. The quote defaults to one currency pair and one amount. That is the right call for the most common journey, but a small business paying suppliers in three countries has a different question. A second worked example for the business path, or a corridor chosen from the visitor’s location, would answer it without clutter.
Where copying backfires. A calculator is a confession booth. If your fees are higher than the market’s, a live quote tells visitors exactly that, in bold. We see teams bolt on a calculator because Wise has one, then watch conversion drop because the numbers were never competitive. Fix the price or show your real advantage — speed, coverage, support — with the same honesty.
Audit check
Can a first-time visitor see what they will pay, what they will get and when, without creating an account?
Failure evidence
“Low fees”, “competitive rates” and “from” prices with asterisks; pricing only after signup or in a sales call.
Correction pattern
Show a worked example with real fees, arrival time and conditions near the main call to action; put any return next to its risk.
Stripe: one headline, four audiences, four front doors
Stripe’s US homepage says “Financial infrastructure to grow your revenue”, then offers “Get started”, “Sign up with Google” and, in the header, “Contact sales”. Lower down, the page splits into its audiences: enterprises, startups and platforms each get their own section, their own proof and their own stories. The integration section asks a very human question: “Don’t code?” Then it offers three routes: no-code tools in the dashboard, a pre-integrated platform, or building your own integration with the APIs.
It is a restaurant that asks at the door whether you want the set lunch, the tasting menu or the private room, instead of handing everyone the same fifty-page menu. The developer, the founder and the procurement lead all arrive at the same address. Each needs a different first step, and each has a different budget attached.

The proof is scale: “$1.9T in payments volume processed in 2025”, “99.999% historical uptime for Stripe services”, customer stories with named brands. For Stripe, those numbers answer the real enterprise fear, which is “will this fall over on Black Friday?” Each customer story also lists the products used, which quietly teaches the visitor how the catalogue fits together without a product diagram nobody reads.
What we would still question. The hero line is broad enough to fit almost any payments company. Stripe can afford that because the brand does the explaining. The audience sections do the real work further down, which means a first-time visitor who never scrolls meets a slogan and two buttons. For a less famous company, the same structure would lose most of its visitors before the useful part.
Where copying backfires. A startup with forty customers copying Stripe’s proof section is a village fete advertising itself with festival attendance figures. Borrowed plumes fool nobody, and the visitor who spots the gap stops believing the rest of the page. Your proof should match your stage: a named design partner, one measured result, a founder’s reachable email. Small and specific beats big and borrowed.
Audit check
List your top three visitor types and follow each from the homepage to its first meaningful action.
Failure evidence
One “Get started” for everyone; developers dumped into a sales form; enterprise buyers pushed into self-serve signup.
Correction pattern
Give each audience its own entry path, proof and call to action, and make the proof match your real stage.
Mercury: the uncomfortable sentence goes next to the button
Mercury’s homepage opens with “Radically different banking” and “Apply online in 10 minutes”, an email field, “Open account” and “Launch demo”. Directly under that form, not in the footer, sits the sentence many fintechs bury: “Mercury is a fintech company, not an FDIC-insured bank. Banking services provided through Choice Financial Group and Column N.A., Members FDIC.”
That is a car dealer telling you in the first line of the brochure that the car is a lease, not a purchase. It feels like bad salesmanship for about three seconds. Then it feels like the first honest thing a finance company has said to you all week. The visitor who needed that fact now has it at the moment they are deciding, and the one who did not need it loses nothing.

Mercury pairs the disclosure with a larger promise: up to $5M of FDIC insurance “through our partner banks and their sweep networks”, with a footnote, and a footer that explains deposit insurance covers the failure of an insured bank. The “Launch demo” button matters as much. It lets a cautious founder see the product before handing over an email, which is how you keep the visitor who is interested but not ready.
What we would still question. The email field above the disclosure asks for commitment before the visitor has seen pricing or the demo, and the form also carries a marketing opt-out checkbox. That is a lot of small print around one input. Letting people reach the demo and pricing first, then asking for the email, would keep the cautious founder in the room a little longer.
Where copying backfires. Moving legal text up the page is only a win if a human can read it. Paste the full compliance paragraph under your hero and you have built a wall, not a window. Write one plain sentence, link to the rest, and get it approved by the people who own the risk.
Chime: every bold claim carries its receipt
Chime’s US homepage makes a big claim in its hero, “America’s #1 Choice for Banking®”, and immediately qualifies it: “Chime is a fintech, not a bank.” The small print says the ranking comes from a Chime survey. Then the feature list works the same way. “Fee-free banking”, cash back and the savings rate each carry a numbered marker that leads to a specific disclosure at the bottom of the page.
This is a medicine advert that reads out the side effects. Nobody enjoys them, but everybody expects them, and an advert without them looks like a scam. In US consumer finance, a “fee-free” claim with no condition attached reads as bait and switch to anyone who has ever been caught by an overdraft fee.

What we would still question. A “#1” claim resting on the company’s own survey is technically disclosed and emotionally weak. Sceptical visitors read “our survey says we’re the best” the same way they read a restaurant’s own five-star sign in the window. The disclosures earn trust; the superlative spends it.
Where copying backfires. Footnotes scale badly. Ten claims with ten markers turn a homepage into a legal document with pictures. If a claim needs three lines of conditions, the claim itself is probably too broad. Narrow the claim until the condition fits in a sentence you would say out loud.
Monzo: price, eligibility and risk on every card
Monzo’s UK homepage, “Spend your money on life, not your life on money”, is a product catalogue, and a disciplined one. Each card carries its price and its conditions. Extra is “£3 a month”, Perks “£9 a month”, Max “From £19 a month” with “Ages 18-69. 3-month minimum term.” The Aura credit card shows its monthly fee and a representative APR. Investments carry “The value of investments and pensions could go up or down, and you could get back less than you invest.” Credit carries “Missed payments may negatively impact credit scores.”
That is the price tag on the shelf instead of at the till. Shoppers who would never pay £19 a month walk past without wasting anyone’s time, and the ones who pick it up already know the deal. The travel section does the same with explanation: pay abroad and the app shows the amount in pounds straight away, “no more napkin maths”. One phrase, and a fear about foreign spending is gone.

Money logic: an application from someone who does not qualify costs you the click, the onboarding steps, the identity check and a support contact, and it still ends in “no”. Eligibility on the card is the cheapest filter you will ever build.
What we would still question. The product cards sit in a carousel with previous and next buttons. Carousels hide most of their content by default, and on a phone the fifth card is effectively invisible. The discipline inside each card deserves a layout that shows more of them at once.
Where copying backfires. A catalogue homepage works for a brand people already know. If nobody has heard of you, twelve product cards say “we do everything”, which a stranger hears as “we are not especially good at anything”. Lead with one job, then show the catalogue.
Audit check
For each product on the homepage, can a visitor see the price, who can apply and the main risk before clicking?
Failure evidence
Applications from ineligible users; “how much does it cost?” as a top support question; risk text only in PDFs.
Correction pattern
Put price, eligibility and a one-line risk note on every product card, in the same type size as the benefit.
Starling: trust from evidence you cannot award yourself
Starling’s UK homepage, “Good with money starts here.”, does something few banks volunteer. Next to its FSCS statement, “Eligible deposits are protected up to £120,000”, and a promise of “24/7 UK support from humans”, it publishes independent service quality survey results, “Published August 2026”, explaining that about 1,000 customers of each of the 17 largest current account providers were asked whether they would recommend their bank. It also links to scam performance data and offers a tool that checks an uploaded screenshot for signs of a scam.
A football club can print “best team in the league” on its scarves. The league table is still pinned up at the ground. Starling’s survey block is required by UK regulation, and plenty of banks treat that requirement like a parking fine. Starling puts it on the homepage and lets the evidence do the talking.

What we would still question. Most of the homepage’s calls to action read “Learn more”, “Tell me more” or a playful variant. They are friendly, but they do not say what happens next. “See the fees” or “Apply, about 10 minutes” would carry the same warmth and tell a cautious visitor what the click costs them.
Where copying backfires. Independent evidence is a double-edged sword. If the survey puts you near the bottom, a homepage block becomes an advert for your competitors. Then the design problem is not the homepage. It is the service, and no layout will fix it.
Brex: numbers with a source and a best-before date
Brex’s homepage, “Finance built for speed and control.”, splits the audience by stage: “Startups”, “Mid-size companies”, “Enterprises”, each with its own pitch. The calls to action split by readiness: “Get started” for people who want in, “See Brex in action” and “See a demo” for people who want to look first.
The proof is where it gets interesting. “756 hours” of average time saved per year, “71%” of expenses handled entirely by automations, and right under them: “These metrics are based on internal metrics from March 2025. Past performance does not guarantee future results, which may vary.” The treasury rate carries a dagger that leads to an explanation of how the number is calculated. Statistics, like milk, have a best-before date, and Brex prints it on the carton. The date is a year and a half old on a 2026 homepage, and that is visible too. Honest, and a reminder to refresh.

Brex also answers a question every B2B fintech fumbles: which button for which visitor. A person who has just heard of you is not ready to “Talk to sales”. A finance lead comparing three vendors does not want a signup form that ends in an onboarding call anyway. Asking for a demo before the visitor knows what you do is proposing on the first date.

What we would still question. Three segment cards promise three different stories, but each leads with a general “Learn more”. A mid-size finance lead has a sharper question than “learn more”: will this replace our current card programme without a six-month migration? Putting the segment’s main fear on the card, and the answer one click away, would make the split pay for itself.
Audit check
For every number on your homepage, write down what it measures, where it comes from and when it was true.
Failure evidence
Round numbers with no source; savings claims nobody on the team can reproduce; one call to action for every stage of readiness.
Correction pattern
Add source and date to each number, remove the ones you cannot defend, and offer a low-commitment path beside the main one.
Website design
Make your fintech website clear to buyers
We rebuild fintech websites around the questions buyers actually ask: who it’s for, what it costs, who holds the money and which button to press.
Plaid: design for the person who never chose you
Plaid is infrastructure. Businesses and developers buy it; millions of consumers meet it inside someone else’s app, on the screen that asks them to connect their bank. Plaid’s European homepage, “Europe’s leading open banking platform”, with “Talk with our team” and “Start building”. It is built for builders. But the navigation carries a small section called “For users”, with “Safety” and “How we handle data”, and the footer states which regulated entities provide the service and that funds are not held by them.
That section exists for the person who has just seen an unfamiliar name on their bank-connection screen and typed it into a search engine, suspicious. It is the substitute teacher’s first five minutes. The class did not choose them, but the class decides whether to trust them, and it decides fast. If that visitor finds a wall of API marketing, they abandon the connection in your client’s app, and your client’s conversion drops.

What we would still question. “For users” sits under a Resources menu, beside blog posts and customer stories. The anxious consumer is the visitor least likely to explore menus. A visible link from the homepage hero, or a search-friendly page title that matches what people actually type, would catch them earlier.
Where copying backfires. A “For users” link in a developer-first navigation is a start, not a finish. If your product appears inside other apps, measure how many people search your name from those screens and build that page like a product page, not a legal page.
Robinhood: good disclosures inside a crowded noticeboard
Robinhood’s US investing page identifies Robinhood Financial beside its stock and fund offer and links to fees and conditions. Its US crypto help names Robinhood Crypto separately, explains that crypto holdings are not FDIC insured or SIPC protected, and includes an investing-risk notice. The reusable design decision is to name the entity and relevant conditions where the visitor evaluates the product, rather than assuming one logo means one protection scheme.
Those entity lines look like legal clutter until you remember what a multi-product fintech is: several regulated companies sharing one logo. Stocks, crypto, a spending account and a credit card can each sit with a different entity and a different protection scheme. A customer who assumes the crypto balance is protected like a bank deposit is a complaint, and possibly a headline, waiting to happen. One short line under the product, in the same place every time, is a cheap way to prevent an expensive misunderstanding.
The competing design risk is a campaign-heavy homepage that gives launches, trading tools, crypto, managed portfolios and educational material similar visual weight. That pattern can leave a newcomer unsure where to begin. It is an airport departure board where every flight is flashing “boarding”. Regular travellers know their gate. First-time visitors stand in the middle of the hall with their bags.

Where copying backfires. A brand with enormous awareness can afford a homepage that talks to existing customers, because newcomers already know what it does. A challenger cannot. Copy the inline disclosures; skip the noticeboard. Monkey see, monkey do is how a startup ends up announcing four launches to visitors who have not yet understood the first product.
Your next reader may be researching with software
A product page should make its offer understandable in ordinary text: what the product does, who it serves, pricing, integrations, trust information and how to start. Keep those facts accessible on the same pages people read, with headings and meaningful links. A separate machine page is not required to make the offer clear.
Finance buyers increasingly ask AI tools to shortlist vendors, compare pricing and summarise security pages. That reader is a mystery shopper who writes the report for your buyer and never shows you the draft. If your homepage says “reimagine your financial future” and hides pricing behind a form, the summary will be vague, and vague does not make a shortlist. Garbage in a pretty font is still garbage in.

Where copying backfires. A separate machine page that says something different from the human page is a trust problem waiting to happen. The fix is boring: clear headings, real prices, named partners and plain product descriptions on the page people see. Machines read that just fine.
Official sources for the examples
The following official pages were rechecked on 5 October 2026: Wise UK, Stripe’s localized homepage, Mercury, Chime, Monzo UK, Starling UK, Brex and Plaid EU. Rates, fees, eligibility and coverage can change; refer to the linked provider terms for current conditions. Use the examples to sharpen your offer, then test your own implemented journey on the devices customers use.
Which patterns travel and which belong to the brand
Borrowing a pattern from a famous site is taking someone else’s prescription. Sometimes it is the same illness and the same dose works. Sometimes the other patient is twice your size and has no allergies. The table below is how we sort them.

The money logic is simple. A pattern that travels removes a reason to leave, so every visitor you already paid for is more likely to reach the next step. A pattern that belongs to the brand only works when the visitor brings their own trust with them. Copy it without that trust and you spend design budget making your page look like a place where visitors expect to find someone else.
The patterns that travel all reduce hesitation: a real price, a plain disclosure near the decision, a condition beside each claim, a path per audience, a dated number, a page for the user who never chose you. The ones that depend on the brand all rely on the visitor already knowing who you are: giant scale numbers, product catalogues, campaign-first heroes, a one-word slogan that means something only because millions of people have the card in their wallet.
Mobile and accessibility: where fintech trust quietly breaks
When campaign traffic arrives on a phone, check where fintech trust can break. The quote calculator that looked elegant at 1440 pixels wraps into a column where the fee sits below the fold. The disclosure next to the button collapses into an accordion labelled “Important information” that nobody opens. Footnote markers become three-pixel targets. Fine print in pale grey on white fails contrast, which is like printing the instructions for the fire extinguisher in pale grey on the back of the fire extinguisher.

Accessible navigation and published accessibility information are useful starting points to inspect on sites such as Wise, Monzo and Starling. That is not an audit, and a skip link does not make a site accessible. It does show that somebody on the team asked the question, which puts them ahead of plenty of fintech launches we are asked to rescue.
Speed is a trust signal too. A money page that stutters, reflows while the fee loads or shows a spinner where the rate should be reads as fragile, and fragile is the last word you want near someone’s savings. Heavy hero video, a carousel of product cards and three tracking scripts are a lot to ask of a mid-range phone on a train. We treat the quote, the price and the disclosure as content that must render first, before any animation, and we test the page on a throttled connection, not on the office Wi-Fi. If the fee appears after the animation, the visitor has already decided what your fees probably are.
For money pages, we test a short list at the moments that matter, not just the homepage hero.

From website promise to the first product screen
The website makes a promise; the product has to keep it on the very first screen. When a homepage says “Apply online in 10 minutes” and onboarding takes fourteen steps and a document upload nobody mentioned, you have booked a hotel from a sea-view photo and been given a room over the car park. Customers do not complain that the website lied. They just abandon onboarding, and your cost per approved account climbs.
This is where fintech website design and product design stop being separate budgets. The claim on the homepage, the steps in onboarding, the words on the first dashboard and the help article all have to describe the same product. On Xcoins, that meant every charge on screen before the confirm button. If your problem sits across that boundary, it is a UI/UX design job, not a homepage refresh.

For the broader principles behind these journeys, from onboarding to transaction states, see our guide to fintech user experience design best practices.
UI/UX design
Great homepage, leaky onboarding?
We design the whole path, from the first headline to the first funded account, so the product keeps every promise the website makes.
Blackstar: explain the investment product before installation
Blackstar connects the website question with the product behind it. After the investment-app redesign, the client returned for a responsive website. A visitor who has not installed the app needs to understand Active Invest, Auto Invest and the product’s features before choosing the next step.
We designed the website from the app’s existing logic and brand, with responsive layouts, a prototype, motion specifications and a brand book. The client’s developers owned implementation; ANODA connected the product logic, responsive website and brand into one design experience.
The reusable decision is continuity: feature names and explanations on the website should prepare visitors for the app they will actually use. Review the marketing page beside the related product screens, then check whether the next action leads where the wording promises. The website design service handles that responsive explanation; fintech design connects it to onboarding and money workflows.
How to use these examples without copying them
Copying the look of a famous fintech site does something nobody intends: it advertises the famous brand. Visitors see the familiar layout, the familiar card, the familiar gradient, and think of the original. You paid for the traffic and they remembered someone else. A forged painting in which the original signature shows through.
Here is the order we work in when a client brings us a folder of screenshots:
- Name the decision behind each screenshot. “Wise shows the fee first” is a decision. “Wise uses green” is not.
- Check whether your product can support it. A price-first hero needs a competitive price; a catalogue needs recognition; scale proof needs scale.
- Find your evidence. Every claim gets a source, a date and a condition. Anything that cannot get one comes off the page.
- Map the paths. One entry path per audience, one call to action per level of readiness.
- Test on a phone with real fees. Where the fee, the disclosure and the button land on a 390-pixel screen decides more than the desktop mock-up.
- Design the visual layer last. Now it can be yours, because it is carrying your decisions, not someone else’s.

If you want to see how we apply this in real projects before starting a conversation, browse our cases. If you need the team that does it, our fintech design practice covers websites, onboarding and the product behind them.
The takeaway
The best fintech websites in this list share no colour, font or layout. They share decisions: say who it’s for, show the price, put the uncomfortable truth next to the button, give every claim its condition, date every number, route each visitor by readiness and keep the promise on the first product screen. A polished hero without those decisions is a paid click with nowhere to go. Buying a pig in a poke is bad enough; asking your visitors to do it with their savings is worse.
None of the examples above is perfect, and that is the useful part. Each one made a clear decision about a specific fear, and each one has a weak spot you can now see. Your own site deserves the same treatment: the same eight questions, a phone, a stopwatch and someone who has never heard of you. Whatever they cannot answer in a minute is the next thing to fix, long before anyone argues about the gradient.
Fintech design
Your competitors’ screenshots won’t explain your product.
Bring us your product, your audience and your regulator’s rules. We’ll turn them into a website and product journey that earns trust and moves the right buyers to the right button.
Written by